Indonesia Export Control Raises Pressure on Panel Supply Costs
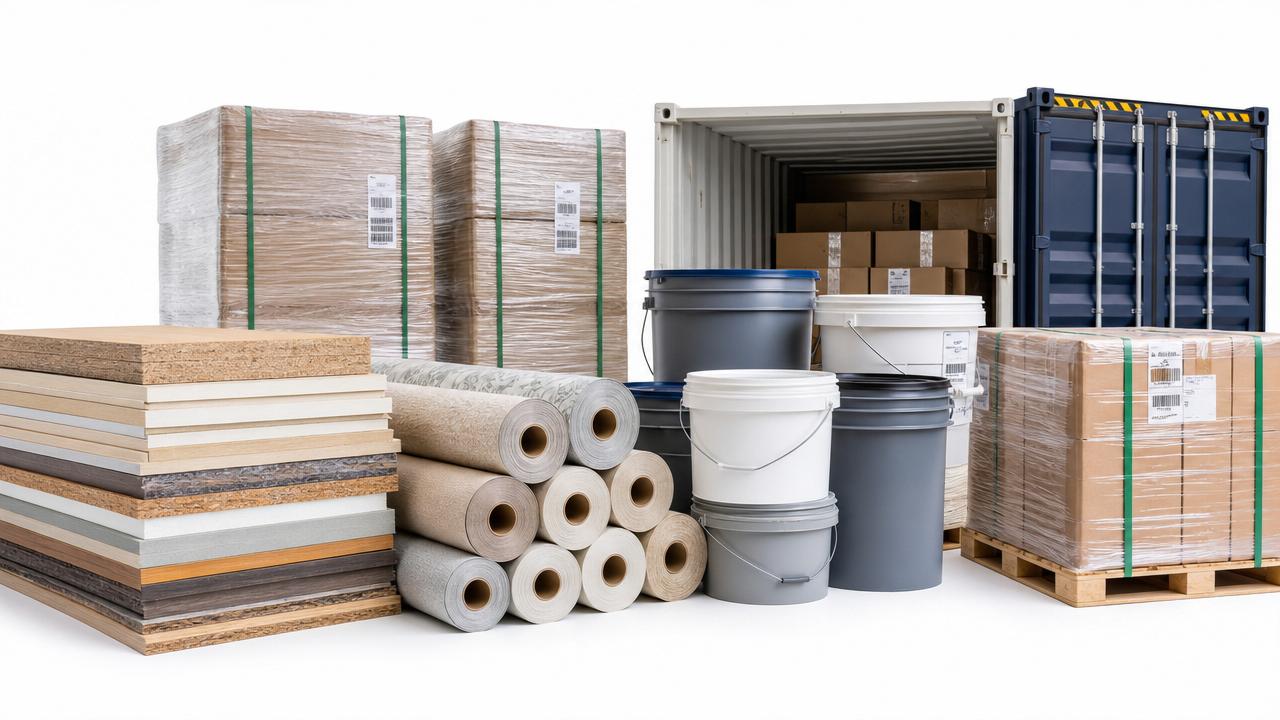
On June 1, 2026, Indonesia began centralized export control over palm oil, coal, and ferroalloys, with PT Darma Henwa designated as the sole export entity in a phased transition through September. For building-material supply chains, the immediate point of attention is not only the export arrangement itself, but also its spillover into imported inputs such as palm oil-based adhesives and flame retardants, which directly affects the cost base and delivery stability of Composite Panel, Wallpapers, and other products that rely on green bonding systems. Manufacturers, traders, supply chain managers, and European and US buyers all need to reassess where pricing pressure and scheduling risk may emerge first.
What has been confirmed so far
According to the provided information, Indonesia has placed exports of palm oil, coal, and ferroalloys under centralized control starting June 1, 2026. PT Darma Henwa has been designated as the only export body, and the handover will proceed in stages until full takeover in September.
The same information states that this change has increased import prices for building-material auxiliaries such as palm oil-based adhesives and flame retardants. It also directly affects the production cost and delivery stability of products including Composite Panel and Wallpapers that depend on green adhesive systems. In response, buyers in Europe and the United States need to re-evaluate the feasibility of alternative production capacity in Southeast Asia.
Where the pressure is likely to appear first
Imported input procurement becomes more exposed
From an industry perspective, companies sourcing palm oil-based adhesives, flame retardants, and related auxiliary materials are among the first to feel the impact. The reason is clear in the provided information: higher import prices for these inputs feed directly into material procurement budgets. What deserves closer attention is whether procurement teams can still maintain original cost assumptions and planned replenishment cycles during the transition period through September.
Manufacturing lines using green bonding systems face tighter cost control
For manufacturers of Composite Panel, Wallpapers, and similar products, the issue is not limited to raw material prices. Analysis shows that products built around green bonding systems may face dual pressure: a higher materials bill and less predictable delivery timing for key inputs. This can affect production scheduling, quotation validity, and the ability to keep lead times stable for downstream customers.
Traders and supply chain coordinators may see contract execution risk rise
For trading companies and supply chain service providers, the main concern is execution. Observably, when an export flow is shifted to a single authorized entity and full takeover is phased in through September, contract timing, document preparation, and shipment coordination become more sensitive points. Even without adding unverified assumptions, the information already indicates that delivery stability is under pressure, which means coordination risk deserves closer monitoring.
European and US buyers may revisit Southeast Asia sourcing assumptions
For overseas buyers, especially in Europe and the United States, the provided information points to a practical sourcing question: whether alternative capacity in Southeast Asia remains commercially workable under the new cost and timing conditions. This does not automatically mean relocation or substitution will occur, but it does mean buyers may need to reassess supplier mix, quotation comparisons, and the reliability of delivery commitments tied to the region.
What companies should watch in the near term
Track the transition from June to September closely
What deserves closer attention is the phased nature of the takeover. The transition period itself matters because business conditions may not remain static between the June 1 start date and the full handover in September. Companies with exposure to the affected materials or products should distinguish between the announced framework and the practical effect on exports, procurement flow, and lead time performance during each stage.
Recheck pricing models for affected product lines
For businesses supplying Composite Panel, Wallpapers, or other products dependent on green adhesive systems, it is more appropriate to review quotations and cost assumptions line by line rather than treating this as a general raw-material issue. The provided information specifically links the export control change to higher import prices for palm oil-based adhesives and flame retardants, so any product family tied to those inputs deserves immediate margin review.
Examine supplier documentation and fulfillment timing
Analysis shows that companies should pay attention to supplier qualification, trade documentation, and fulfillment cycle management. Because the export arrangement is being centralized under a single entity, procurement and logistics teams may need to confirm whether existing paperwork, scheduling expectations, and delivery commitments remain aligned with actual shipment conditions during the transition.
Prepare earlier customer communication where delivery stability matters
For sales teams and account managers, the most practical near-term task may be communication. Where products are sensitive to cost changes or schedule volatility, it is more appropriate to alert customers early that input-side conditions are changing and may require updated lead-time or pricing discussions. This is particularly relevant for export-oriented business serving European and US buyers that are already reassessing alternative capacity options in Southeast Asia.
Why this matters beyond a single trade measure
As an editorial observation, this development should not be read only as a narrow export administration adjustment. Based on the provided information, it already has a direct link to input pricing and delivery stability in parts of the building-material supply chain. That makes it a business-operational issue, not just a policy headline.
At the same time, it is more appropriate to understand this as an industry dynamic still unfolding rather than a fully settled long-term outcome. The control measure has started, the phased handover runs through September, and the impact described so far centers on rising auxiliary-material costs and pressure on production and delivery planning. Whether the effect remains transitional or develops into a more durable sourcing shift still requires continued observation.
How the market may best interpret the signal for now
The current signal is clear: a change in Indonesia's export control framework is already putting cost and scheduling pressure on supply chains connected to palm oil-based adhesives, flame retardants, Composite Panel, and Wallpapers. For companies operating in these segments, the most reasonable interpretation today is neither to overstate disruption nor to dismiss it as temporary noise.
Instead, this should be viewed as a near-term operational risk with possible broader sourcing implications if pricing pressure and delivery instability persist through the transition to September. In practical terms, the event is best understood as both an immediate supply-chain management issue and a policy-linked market signal that merits continued verification.
Basis of this article and points for follow-up verification
This article is based on the user-provided news title, event date, and event summary. The specific official source link was not provided in the input, so the details should continue to be verified against relevant materials typically associated with this type of development, such as official announcements, corporate disclosures, industry association updates, authoritative media reporting, and related trade or standards documentation.
For follow-up observation, the main areas to monitor are the June-to-September transition process, any further clarification in export control implementation, and whether the reported impact on input prices, production costs, and delivery stability continues or changes over time.
Industry Briefing
Get the top 5 industry headlines delivered to your inbox every morning.