Global Building Materials Price Index Rises 2.1% MoM in May
The Global Building Materials Price Index (GBPI) rose 2.1% month-on-month in May 2026, according to the index report released on May 19, 2026. This shift reflects tightening supply conditions in key upstream segments—particularly natural stone from Southeast Asia and motor driver chips for smart toilets in Europe—and warrants close attention from importers, manufacturers, distributors, and procurement teams across global construction supply chains.
Event Overview
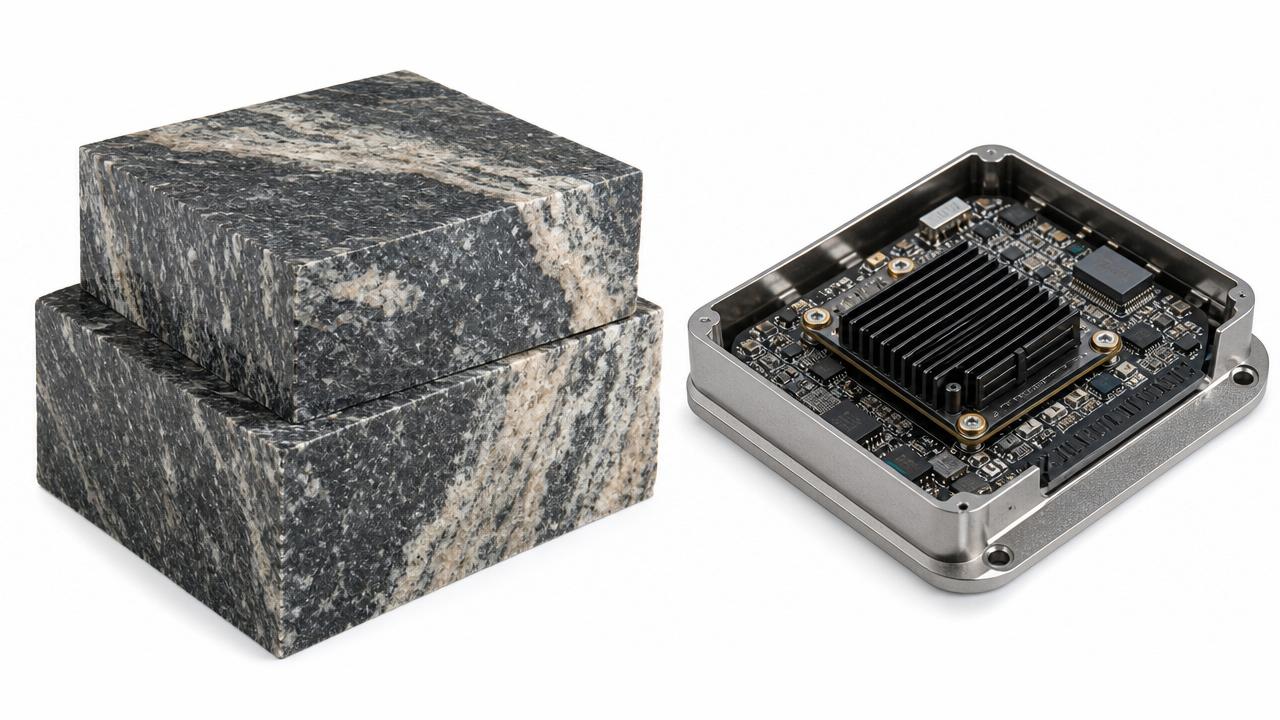
The Global Building Materials Price Index (GBPI) published its May 2026 monthly report on May 19, 2026, showing a 2.1% month-on-month increase in the composite index. The rise was driven by two confirmed factors: (1) Indonesia and Vietnam jointly tightened export quotas for granite rough blocks, pushing FOB prices for natural stone up by 8.3%; and (2) STMicroelectronics suspended supply of the STSPIN32F0B motor driver chip to European smart toilet brands, extending lead times for smart toilet seats to 14 weeks and elevating end-market pricing. These developments have prompted quarterly procurement budget reassessments among distributors in Europe and North America.
Impact on Specific Industry Segments
Direct Trading Enterprises
Companies engaged in cross-border trade of natural stone—especially those sourcing granite from Indonesia or Vietnam—are facing immediate margin pressure due to the 8.3% FOB price increase. Quota restrictions directly reduce available volume per shipment, increasing competition for allocated slots and raising transactional overhead.
Raw Material Procurement Teams
Procurement units sourcing critical electronic components for smart bathroom products are affected by the STSPIN32F0B supply suspension. With no alternative qualified chip currently indicated in public disclosures, procurement cycles for smart toilet assemblies are now constrained by component availability—not assembly capacity.
Manufacturing Enterprises (Smart Sanitaryware)
European manufacturers integrating smart toilet seats into finished products face extended production planning horizons. A 14-week lead time for a core component disrupts just-in-time manufacturing models and increases working capital requirements for inventory buffering.
Distribution & Channel Enterprises
Wholesalers and regional distributors serving residential and commercial renovation markets in Europe and North America are revising Q2 2026 procurement budgets. Longer lead times and higher landed costs for both stone cladding and smart fixtures are triggering earlier price negotiations and revised order timing with downstream contractors.
What Stakeholders Should Monitor and Act On
Track official policy updates from Indonesian and Vietnamese trade authorities
Quota adjustments are administrative measures; any formal extension, revision, or exemption framework would be announced through national customs or mining ministry channels. Monitoring these sources helps distinguish temporary enforcement actions from structural export policy shifts.
Monitor chip allocation status and substitution efforts for STSPIN32F0B
STMicroelectronics’ supply suspension is product-specific and not industry-wide. Stakeholders should verify whether alternative qualification pathways (e.g., second-source validation or firmware adaptation) are underway—and whether competing chips (e.g., Infineon’s IFX007T or ON Semiconductor’s LV8548MC) are being certified for use in certified smart toilet platforms.
Differentiate between price signal and sustained cost pass-through
The 2.1% GBPI increase reflects aggregated spot-level movements. Not all downstream categories will experience proportional pricing effects. For example, fabricated stone products may absorb part of the raw material increase, while commoditized smart toilet SKUs may see faster price transmission due to tighter channel inventory.
Adjust procurement timelines and buffer stock strategies for high-impact SKUs
Importers and manufacturers reliant on Indonesian/Vietnamese granite or STSPIN32F0B-dependent smart toilet modules should extend ordering windows by at least 4–6 weeks and consider holding safety stock for top-three revenue-generating SKUs—not broad-category buffers—to mitigate near-term delivery risk without overcapitalizing inventory.
Editorial Observation / Industry Perspective
Observably, this GBPI movement functions less as an isolated price spike and more as a dual-signal event: first, a reminder that localized resource governance (e.g., mineral export quotas) continues to exert measurable influence on globally traded construction inputs; second, a demonstration that single-component dependencies—even in mature electronics supply chains—can propagate delays far beyond semiconductor fabs into finished building product timelines. Analysis shows the current impact remains concentrated in specific nodes (granite sourcing, smart toilet drive systems), rather than systemic inflation across broader building materials categories. From an industry standpoint, the May 2026 GBPI reading is best understood not as a trend inflection point, but as a stress-test outcome highlighting existing vulnerabilities in two non-substitutable supply lanes.
This update underscores how regulatory and technical dependencies—rather than macroeconomic drivers alone—now shape near-term procurement planning in building materials markets. It does not indicate broad-based inflationary pressure, but rather targeted constraint in two vertically narrow yet commercially significant segments. Current conditions favor scenario-aware planning over reactive repricing.
Information Source: Global Building Materials Price Index (GBPI) Monthly Report, May 2026 edition, published May 19, 2026. Note: Quota implementation details from Indonesian Ministry of Energy and Mineral Resources and Vietnamese Ministry of Industry and Trade remain under active monitoring; STMicroelectronics’ supply status is based on verified brand-level procurement advisories issued in mid-May 2026.
Industry Briefing
Get the top 5 industry headlines delivered to your inbox every morning.