Vietnam Building Materials Exports Face Longer Middle East Lead Times
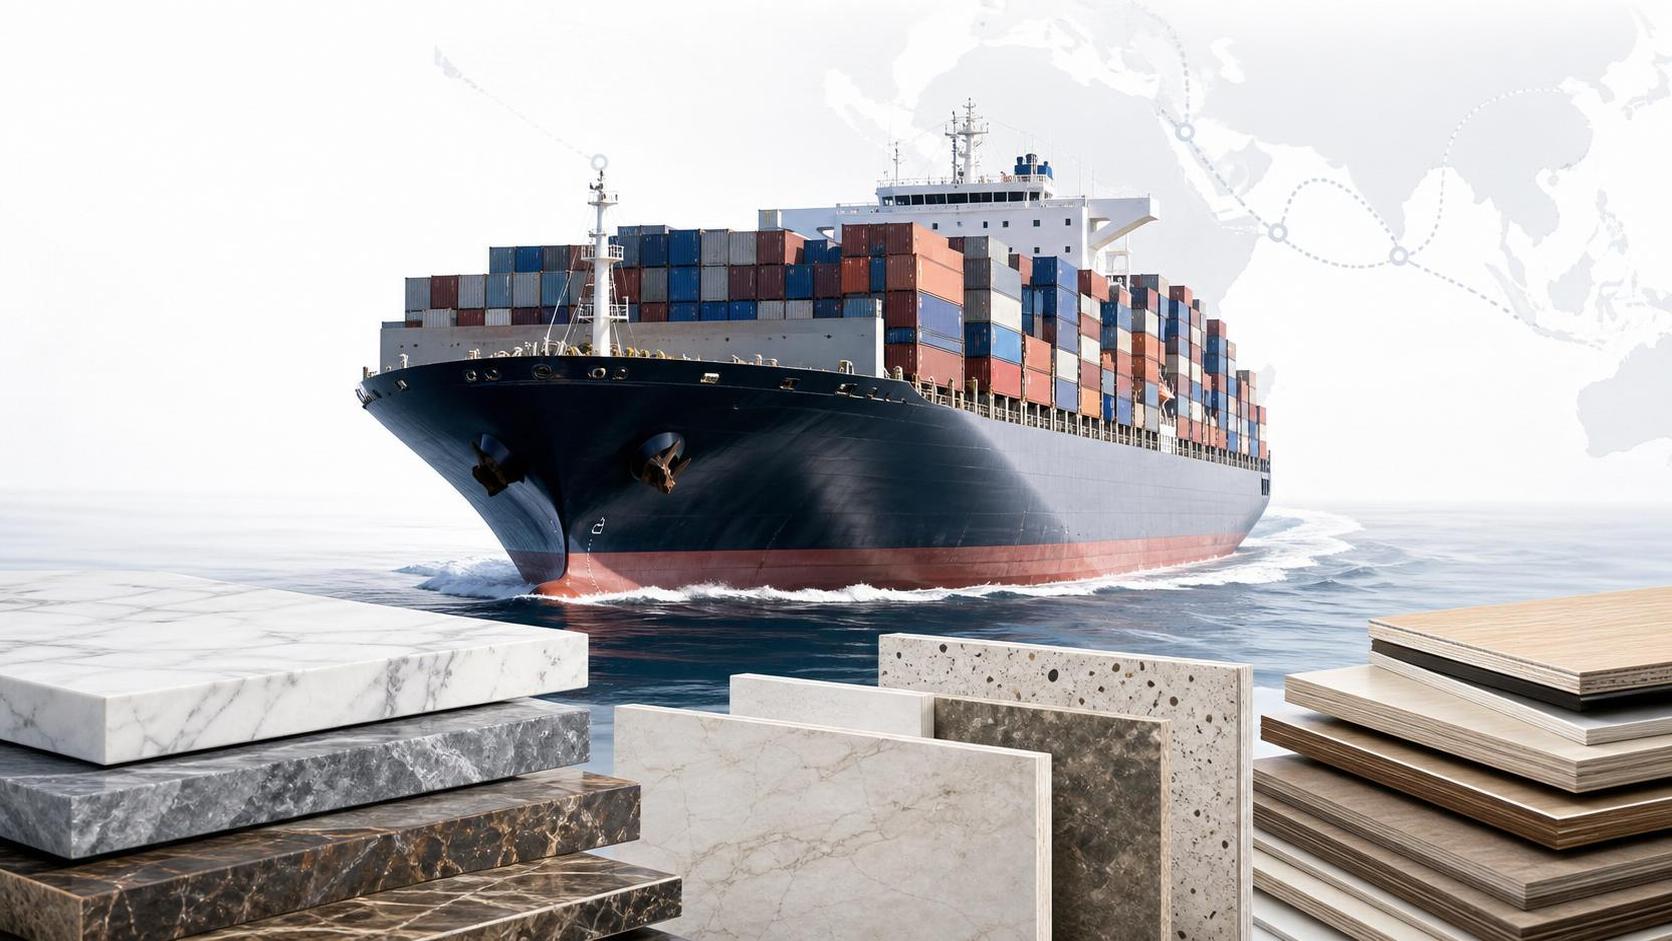
The timing of this disruption has not been specified in the available information, but the development is already relevant for exporters, buyers, and logistics providers tied to Vietnam’s building materials trade with the Middle East. As shipping lines suspend routes through the Strait of Hormuz amid escalating geopolitical tensions in the region, shipments of natural stone and composite decorative panels from Vietnam are being diverted around the Cape of Good Hope, extending delivery schedules and raising freight-related costs in ways that directly affect order execution.
What has changed in the shipping route
Based on the provided information, several international shipping companies have suspended routes through the Strait of Hormuz because of escalating geopolitical conflict in the Middle East. As a result, Vietnamese exports of natural stone and composite decorative panels to the Middle East are being rerouted around the Cape of Good Hope.
This diversion adds about 4,200 nautical miles to a one-way voyage. The current average delivery cycle has been extended by 12 to 18 days, while freight surcharges have increased by 35% to 60%. The same information also indicates that some low-margin orders have already moved into immediate loss.
Where the pressure is likely to appear first
Exporters are facing a direct contract-performance challenge
From an industry perspective, direct trading companies are likely to feel the impact first because the disruption affects the most visible parts of execution: shipment timing, freight cost, and margin protection. For exporters of natural stone and composite decorative panels, the longer voyage changes the practical delivery window and can quickly weaken the economics of orders that were priced under earlier shipping assumptions.
Processors and manufacturers may need to reassess production timing
Analysis shows that processing and manufacturing businesses connected to these exports may also be affected, even though the route disruption happens at sea rather than on the factory floor. If delivery windows move by nearly two weeks or more, production release, packing schedules, and dispatch sequencing may need closer coordination with confirmed vessel plans and customer deadlines.
Importers and project buyers in the Middle East may need to watch delivery certainty
For buyers, distributors, and project-side procurement teams in the destination market, the main issue is not only a slower shipment but also reduced certainty around arrival timing and landed cost. What deserves closer attention is whether products tied to fixed installation or resale schedules can still match the required timeline once rerouting and surcharges are factored in.
Logistics service providers are under pressure to manage exceptions
Supply chain service providers are also drawn more deeply into execution risk. The rerouting itself, the longer transit path, and the rise in surcharges mean freight coordination, booking stability, and shipment updates become more sensitive parts of customer service than under normal route conditions.
What companies should monitor now
Recheck lead times against active orders
Companies serving the Middle East market should closely compare the newly extended 12 to 18 day delivery window with the commitments already made to customers. This matters most for orders with fixed handover dates, narrow installation windows, or pricing that leaves little room for delay-related cost absorption.
Review margin exposure on low-profit shipments
The provided information already shows that some low-margin orders have entered immediate loss. Analysis shows this makes order-level profitability review a near-term priority, especially where freight surcharges of 35% to 60% materially alter the original quotation logic.
Strengthen shipment communication and documentation control
Observably, when route conditions change suddenly, communication discipline becomes a practical risk-control tool. Exporters, buyers, and service providers should pay closer attention to shipment status updates, delivery expectation resets, and the consistency of supporting documents tied to fulfillment timing and commercial terms.
Track whether route conditions stabilize or remain restricted
What deserves closer attention is not only the current delay but also whether the routing change proves temporary or persists for a longer period. That distinction matters because short-term disruption can often be managed operationally, while a prolonged shift would affect pricing, scheduling, and customer negotiations more structurally.
Why this matters beyond one delayed shipment cycle
Observation and analysis suggest this is more than a simple freight delay notice. It shows how quickly geopolitical risk in a key shipping corridor can translate into longer lead times and immediate margin stress for building materials trade that depends on predictable ocean transport.
At the same time, it is more appropriate to understand this as a developing industry dynamic rather than a finalized long-term market outcome. The confirmed facts establish route diversion, longer transit time, higher surcharges, and losses on some low-margin orders, but the duration and full commercial ripple effects still require continued observation.
How the market should read this signal
For the building materials sector, the current signal is clear: logistics disruption can rapidly become a pricing and fulfillment issue, especially for products such as natural stone and composite decorative panels that move through export projects and scheduled deliveries. A neutral reading is that this development currently fits best as a short-term operational shock with the potential to become a wider commercial issue if rerouting and elevated freight costs continue.
In that sense, the news deserves attention not because it confirms a permanent shift, but because it highlights where execution risk is now concentrated across the export chain.
Basis of this article and points for follow-up verification
This article is generated solely from the user-provided news title, event timing note, and event summary. The specific official source link was not provided in the input, so the underlying details still need ongoing verification against source materials that may typically include official announcements, company statements, industry association updates, authoritative media reporting, or other formal trade-related disclosures.
For follow-up observation, the most relevant points are whether shipping restrictions through the Strait of Hormuz continue, whether rerouting remains necessary, and whether the reported delivery extension and freight surcharge pressure persist across subsequent shipments.
Industry Briefing
Get the top 5 industry headlines delivered to your inbox every morning.