Indonesia Q2 Tile Imports Rise 21.3% as Premium Glazed Demand Grows
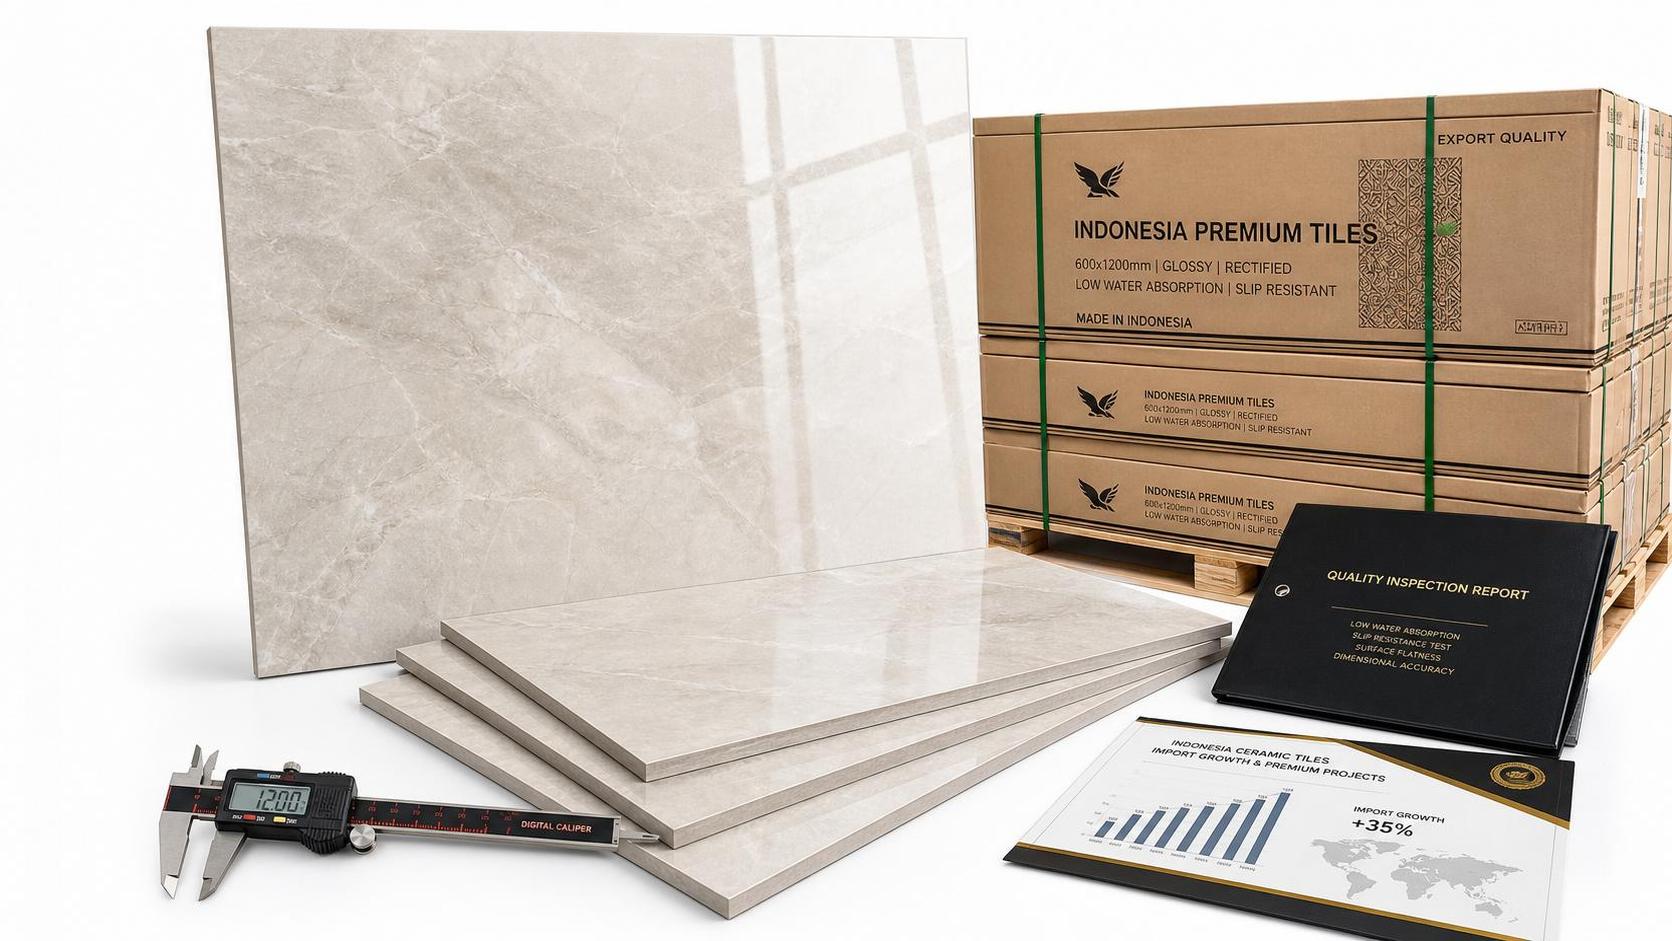
Indonesia's latest Q2 import release from BPS, published on July 9, 2026, is more than a trade data update for the tiles and ceramics market. It provides an execution-level signal for import planning, product specification alignment, and compliance review across exporters, buyers, distributors, and supply chain service providers. The sharp rise in overall import value and the higher share of polished glazed porcelain point to a market shift that can affect procurement priorities, technical documentation, delivery planning, and the way suppliers position products for mid- to high-end residential and commercial demand.
What the BPS release confirms
According to the Q2 2026 import statistics issued by Indonesia's Central Statistics Agency (BPS) on July 9, 2026, total imports of Tiles & Ceramics reached USD 872 million, up 21.3% year on year. Within that total, polished glazed porcelain accounted for 44% of imports. The summary indicates that this category mix reflects structural growth in demand from mid- to high-end residential and commercial projects for anti-slip, low water absorption, and large-format ceramic products. China remained the main supplying country, with a stable share of 63.5%.
Where the immediate pressure points may emerge
Export-facing suppliers may need tighter specification matching
Analysis shows that suppliers serving the Indonesian market may be affected first at the product and documentation level. A higher share for polished glazed porcelain suggests that technical attributes such as anti-slip performance, low water absorption, and large-format suitability may carry more weight in buyer screening and procurement comparison. What deserves closer attention is whether product descriptions, technical sheets, quality records, and shipment documentation are sufficiently aligned with the imported category mix now visible in official trade data.
Import buyers and project procurement teams may revise purchasing priorities
From an industry perspective, procurement teams for residential and commercial projects may feel the impact in sourcing structure rather than in headline volume alone. The published data does not introduce a new formal regulation by itself, but it can influence how buyers evaluate supplier capability, product consistency, and delivery readiness for higher-specification tiles. In practice, that means closer review of product certification status, test-related materials, technical submissions, and bid documents where project requirements are becoming more quality-sensitive.
Distributors and channel operators may face a more selective product mix
Observably, distributors and channel businesses may need to pay attention to assortment decisions and inventory planning. When a larger share of imports is concentrated in polished glazed porcelain, channel participants may need to review whether their stocked items, labeling materials, and downstream sales documentation match the categories showing stronger demand. The business effect is likely to appear in SKU selection, replenishment timing, and after-sales handling for more specification-driven products.
Logistics and supply chain service providers may see stricter delivery coordination
Analysis shows that supply chain service providers are also exposed, particularly where project-linked orders require tighter coordination between product specification, shipping documents, and delivery schedules. Even without a newly announced regulatory text in the input, official import data of this kind can shape customs preparation, goods classification attention, and document accuracy expectations. Service providers should therefore watch for changes in customer requests around product details, batch traceability, and supporting paperwork.
What companies should review now
Recheck compliance files against product positioning
What deserves closer attention is whether compliance and technical files match the products being promoted into Indonesia. For suppliers targeting polished glazed porcelain demand, it is prudent to review product descriptions, quality records, and any certification or testing materials already used in sales and tender processes. This is not because the input confirms a new certification rule, but because the market signal now points more clearly toward higher-specification products.
Track official wording and buyer-side execution signals
Observably, companies should monitor how official trade reporting is reflected in buyer behavior, procurement language, and market-facing requirements. The current information confirms a demand and import structure change, but it does not provide detailed implementing rules, technical thresholds, or revised compliance instructions. That means businesses should treat future official wording, customer specifications, and tender documents as key follow-up indicators.
Prepare documentation for specification-led procurement
From an industry perspective, one practical response is to improve readiness of technical documents used in pre-sale and delivery stages. Where projects are increasingly focused on anti-slip, low water absorption, and large-format characteristics, procurement teams and exporters may need cleaner product data packs, more consistent shipment records, and stronger linkage between catalog claims and deliverables. This is especially relevant when buyers compare multiple suppliers under tighter project requirements.
Review delivery and after-sales risk for higher-end categories
Analysis shows that stronger demand for premium tile categories can increase scrutiny after delivery as well as before shipment. Companies should therefore pay attention to supplier qualification, delivery consistency, and traceability support in case product quality questions arise downstream. The input does not confirm any new enforcement action, so this should be understood as a risk-control measure rather than a confirmed regulatory change.
Why this looks more like an execution signal than a closed rule change
Observably, this development is best read as a market and execution signal emerging from official import statistics, rather than as a fully defined new policy framework. The data shows a clearer direction in imported product structure and sourcing concentration, which can influence procurement standards, compliance attention, and supplier competition. At the same time, the input does not provide new regulatory text, updated certification rules, or a revised customs requirement. For that reason, continued observation is still necessary before treating this as a settled rule change.
How the market should read this stage
At this stage, the BPS release matters because it captures a measurable shift in Indonesia's tile import mix and highlights where trade and project demand are concentrating. A rational reading is that the market is sending stronger signals around higher-specification ceramic products, with likely consequences for sourcing, documentation, and delivery discipline. It is more appropriate to understand this as a confirmed data-based change in market execution conditions, while the downstream compliance and procurement implications still require close monitoring.
Source basis and what still needs verification
This article is generated based on the user-provided news title, event date, and event summary. For developments of this kind, relevant source types typically include official announcements, releases from regulatory authorities, customs or trade administration updates, industry association information, standards organization documents, and reporting by established media. A specific official source link was not provided in the input and still needs to be verified on an ongoing basis. Follow-up attention should remain on any later policy detail, certification interpretation, tender document changes, market feedback, and how companies implement related trade and compliance adjustments in practice.
Industry Briefing
Get the top 5 industry headlines delivered to your inbox every morning.