SCFI Slips Below 1200 as China-Middle East Rates Fall
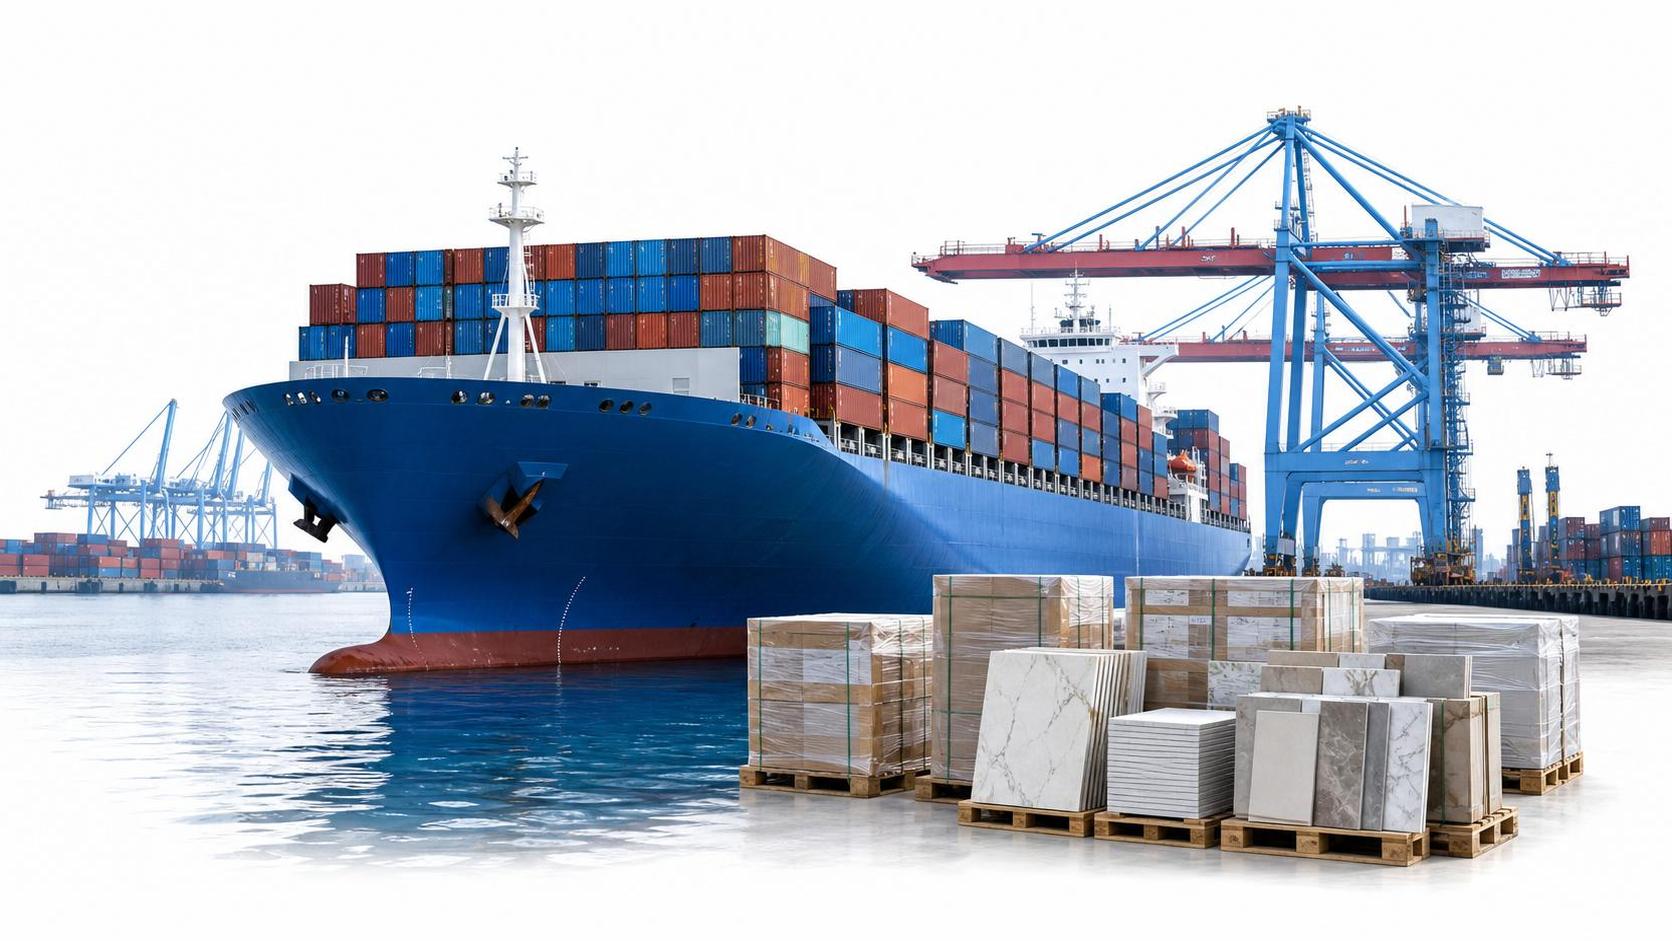
On June 28, 2026, the Shanghai Containerized Freight Index (SCFI) closed at 1186.3, while freight rates on the China-Middle East route fell 17.9% week on week to their lowest level since October 2025. For exporters in tiles, ceramics, and natural stone, this is worth close attention because looser shipping capacity can improve delivery flexibility and freight cost control, especially in shipment models that rely on LCL consolidation and smaller, more frequent replenishment orders.
What the latest freight reading confirms
The confirmed facts are limited but clear. The SCFI closed at 1186.3 on June 28, 2026. On the same date, the China-Middle East route recorded a weekly decline of 17.9%, reaching its lowest point since October 2025. The summary provided attributes this move to normalized Red Sea detours combined with the commissioning of new berths at Jebel Ali Port in Dubai, which has contributed to looser vessel capacity on the route.
The same information also indicates that this freight environment has improved the shipment window and freight cost control conditions for exporters of tiles, ceramics, and natural stone, with particular relevance for LCL and small-batch, high-frequency replenishment models.
Where the pressure eases across the export chain
Exporters gain more room in shipment planning
From an industry perspective, direct trading companies shipping tiles, ceramics, and natural stone to Middle East markets are likely to feel the impact first. The reason is straightforward: when route rates fall sharply and capacity conditions loosen, the most immediate effect appears in booking flexibility and delivery scheduling. What deserves closer attention is whether this translates into smoother shipment timing for urgent replenishment, mixed-container orders, and lower-volume transactions.
Manufacturers may benefit in delivery coordination
Processing and manufacturing companies are also likely to be affected because freight conditions influence how production schedules align with dispatch timing. Analysis shows that a more relaxed shipping environment can improve the handoff between factory completion and outbound shipment, particularly for exporters managing varied order sizes. The practical impact is less about production itself and more about the coordination of finished goods, packing, and dispatch windows.
Logistics service providers face a different operating rhythm
Supply chain service providers, especially those involved in consolidation and booking execution, may see changes in shipment structure. Observably, LCL and small-batch replenishment models become more workable when freight costs and booking pressure ease. The point to watch is not only lower rates, but whether customer booking behavior shifts toward more frequent and smaller shipments rather than larger, less frequent lots.
Buyers and channel operators may see more flexible replenishment options
For buyers, distributors, and channel operators in destination markets, the main relevance lies in delivery responsiveness. Analysis shows that lower route pressure can support tighter replenishment cycles, especially where order patterns are fragmented or demand timing is less predictable. That said, this should be treated as a potential operating advantage rather than a guaranteed market outcome.
What companies should monitor now
Track whether lower rates hold long enough to affect quoting
What deserves closer attention is whether the latest rate decline remains stable enough to influence export quotations and customer negotiations. A single weekly move is meaningful, but companies still need to distinguish between a short-lived pricing adjustment and a sustained shift in route conditions.
Review LCL and small-batch order execution
For tile, ceramics, and natural stone exporters already serving smaller, more frequent orders, this is a practical moment to review how LCL bookings, shipment batching, and dispatch frequency are being managed. Analysis shows that the current freight setup is especially relevant for businesses that depend on replenishment flexibility rather than large-volume shipment cycles.
Recheck delivery commitments and client communication
Where delivery windows improve, sales and operations teams should pay attention to how shipment timing is communicated to customers. The issue is not simply cost reduction; it is whether improved shipping conditions allow more reliable commitment on dispatch timing, order splitting, or replenishment cadence.
Keep documentation and execution discipline in place
Even when freight conditions improve, execution quality still matters. Exporters and service providers should continue to watch booking arrangements, shipment documentation, and fulfillment timing closely. Observably, better capacity conditions can create more room for action, but they do not remove the need for disciplined coordination across order handling and outbound execution.
Why this looks like an operational signal, not a final trend
Analysis shows that this development is best understood first as an operational signal for the China-Middle East route rather than as a settled long-term trend. The drop below 1200 in SCFI and the sharp weekly fall on the China-Middle East lane point to a meaningful easing in freight conditions, but the confirmed facts are still limited to one index reading, one weekly route movement, and the stated supply-side drivers.
It is more appropriate to understand this as a development that can immediately affect shipment planning for relevant exporters, while still requiring continued observation before drawing broader conclusions about long-term freight direction. For tiles, ceramics, and natural stone businesses, the immediate value lies in execution flexibility rather than in assuming structurally lower logistics costs from this point onward.
How this update should be read by the market
In practical terms, this update matters because it points to a more favorable shipping window for exporters serving Middle East routes, especially those handling LCL cargo and frequent replenishment orders. The significance is not that every part of the supply chain will benefit equally, but that freight conditions appear to be giving certain export models more room to operate.
At this stage, the most balanced reading is that the development offers a useful short-term operating advantage and a route-specific signal worth monitoring further. It should not yet be treated as a definitive long-term reset, but it is relevant enough for exporters, manufacturers, and logistics providers to adjust near-term planning.
Basis of this article and what still needs verification
This article is based on the user-provided news title, event date, and event summary. The confirmed inputs include the June 28, 2026 SCFI closing level, the 17.9% weekly fall on the China-Middle East route, the fact that this was the lowest level since October 2025, the stated reasons related to normalized Red Sea detours and new berth capacity at Jebel Ali Port, and the indicated implications for tiles, ceramics, and natural stone exporters.
Specific official source links were not provided in the input and still require ongoing verification. For this type of industry update, commonly relevant source categories may include official market index releases, company announcements, industry association updates, authoritative media coverage, and other formal shipping or trade-related disclosures. The next points to watch are whether the route-level freight trend continues, whether capacity conditions remain loose, and whether the reported operational benefits for LCL and small-batch replenishment models persist over time.
Industry Briefing
Get the top 5 industry headlines delivered to your inbox every morning.