Suez Canal Fees Rise 32% as Building Materials Drop in Priority
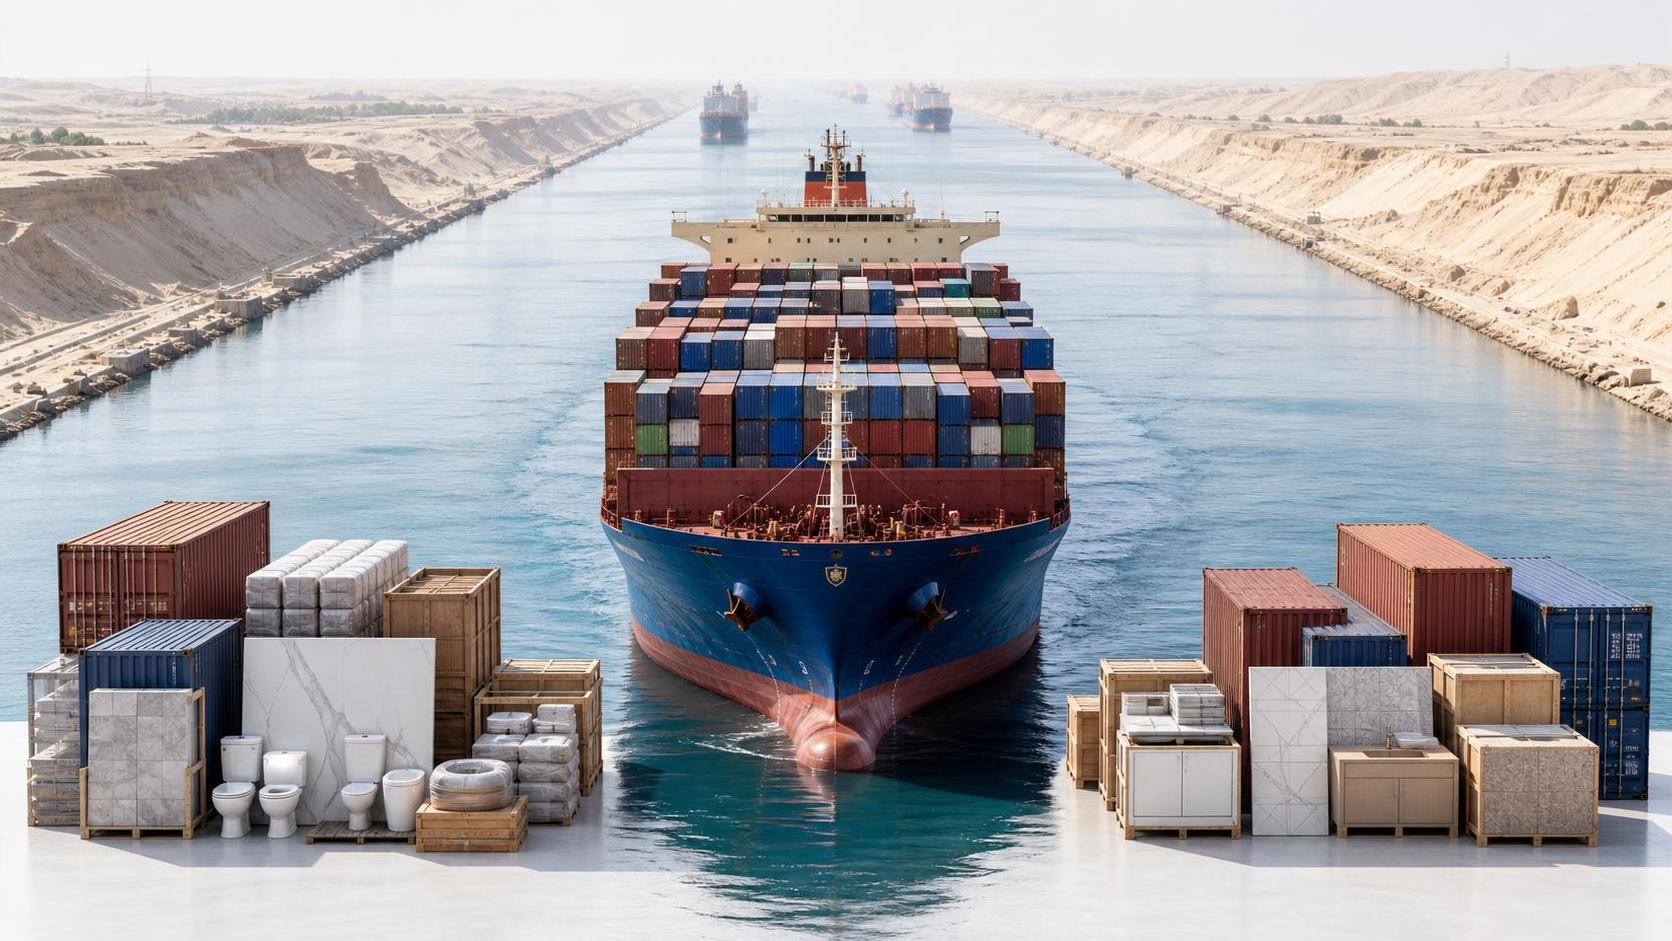
On June 26, 2026, the Suez Canal Authority announced that transit fees for non-energy container ships will rise by 32% from June 28, while a new cargo-priority mechanism places building materials, including ceramic tiles, sanitary ware, and cabinets, in Tier-3 low priority. For exporters, importers, manufacturers, and logistics providers tied to Europe-Asia trade, this matters because the change combines higher route costs with longer waiting times, while the FBX spot rate index for the Asia-Europe lane jumped 28% in a single week and ceramic export lead times broadly stretched by two to three weeks.
What Has Changed in the Suez Transit Rules
According to the confirmed information provided, the Suez Canal Authority (SCA) stated on June 26, 2026 that, effective June 28, transit fees for non-energy container vessels will increase by 32%.
At the same time, the SCA introduced a cargo-priority mechanism. Under this arrangement, building-material cargoes, including tiles, sanitary ware, and cabinets, are classified as Tier-3 low priority.
The average waiting time for this cargo category is reported at 72 to 96 hours. During the same period, the FBX spot freight index on the Asia-Europe route rose 28% week on week, and ceramic export delivery schedules were broadly delayed by two to three weeks.
Where the Pressure Is Likely to Be Felt First
Exporters face a combined cost-and-time squeeze
From an industry perspective, direct trading companies handling ceramics and sanitary ware may be among the first to feel the impact because the confirmed changes affect both transit cost and queue priority. The immediate business pressure is likely to appear in freight budgeting, shipment scheduling, delivery commitments, and customer-side lead-time management.
What deserves closer attention is whether orders already priced on earlier freight assumptions can still be executed without margin pressure or renegotiation pressure.
Manufacturers may see disruption move upstream into production planning
Analysis shows that processing and manufacturing enterprises are exposed even when the disruption occurs at the shipping stage. If export lead times for ceramics are already extending by two to three weeks, the effect may flow back into factory dispatch planning, finished-goods storage, packing schedules, and production sequencing for export-bound orders.
The key issue is not only whether goods can be produced on time, but whether shipment timing and customer-required delivery windows remain aligned.
Logistics and supply chain service providers will need tighter coordination
For freight forwarders, booking agents, and other supply chain service providers, the reported fee increase and lower cargo priority suggest more pressure on booking arrangements, vessel selection, transit timing, and exception handling. Longer waiting periods for Tier-3 cargoes can affect schedule reliability and communication frequency across shippers, carriers, and consignees.
Observably, service performance will be judged less by nominal transit plans and more by how quickly disruptions are identified and communicated.
Buyers and distribution channels may need to adjust inventory expectations
Importers, distributors, and project-side buyers connected to ceramic and sanitary products may also be affected because a two-to-three-week delay in export lead time can alter replenishment timing and downstream delivery expectations. The most relevant business links are purchasing cycles, warehouse receipt planning, and customer delivery coordination.
What deserves closer attention is whether the delay remains a short-term logistics issue or starts affecting normal procurement rhythm in key destination markets.
What Companies Should Watch Now
Track whether the priority framework changes in wording or execution
Analysis shows that companies should closely monitor any follow-up official wording around the cargo-priority mechanism, especially how Tier-3 treatment is applied in practice. A formal category label and its real operational impact are not always identical, so execution details matter as much as the announcement itself.
Review products and orders most exposed to the Suez route
Businesses with concentrated exposure in ceramic tiles, sanitary ware, cabinets, and other building-material shipments should identify which orders are most sensitive to longer waiting times and higher freight costs. The focus should be on shipments with fixed delivery dates, narrow margins, or customer contracts tied to specific handover windows.
Recheck documents, lead times, and customer communication
From a practical standpoint, extended waiting times increase the importance of document readiness, shipment timing buffers, and clear customer communication. Companies may need to revisit promised delivery dates and ensure that internal planning reflects the latest known transit conditions rather than earlier assumptions.
Separate policy signals from actual shipment outcomes
Observably, firms should avoid treating the announcement alone as the full picture. The fee increase, the low-priority classification, the freight index movement, and the reported delivery delays together form the current signal, but actual business impact still depends on how these elements translate into individual shipments and contracts.
Why This Matters Beyond a Single Freight Adjustment
It is more appropriate to understand this as more than a simple shipping surcharge. Analysis shows that the combination of a 32% transit fee increase, lower cargo priority for building materials, and a sharp weekly move in the Asia-Europe spot freight index signals a logistics environment in which ceramics and sanitary ware are becoming less favored in route allocation and more vulnerable to schedule slippage.
At the same time, this should not yet be overstated as a settled long-term outcome. Based on the confirmed information, the market already has visible signs of pressure, but the duration and depth of the disruption still require continued observation.
How to Read the Current Signal
In neutral terms, this development points to a clear near-term risk for building-material exporters using the Suez route: higher costs, longer waits, and weaker delivery certainty are now appearing together rather than separately. For the ceramics and sanitary ware trade, the more reasonable reading at this stage is that this is an active industry signal with immediate operational consequences and continuing uncertainty, rather than a temporary detail that can be ignored or a fully settled structural shift.
Basis of This Article and What Still Needs Verification
This article is based on the user-provided news title, event date, and event summary. The confirmed facts used here come from the provided description of the SCA announcement, the reported cargo-priority classification, the stated waiting-time range, the FBX weekly movement, and the reported delay in ceramic export lead times.
For this type of industry update, commonly relevant source categories may include official notices, company announcements, trade association updates, authoritative media coverage, and standard-setting or transport-related institutional documents. A specific official source link was not provided in the input, so further verification remains necessary.
The points that still deserve continued tracking include whether the cargo-priority mechanism is revised, whether waiting times remain within the reported range, and whether the current freight and delivery disruption persists or changes in subsequent weeks.
Industry Briefing
Get the top 5 industry headlines delivered to your inbox every morning.