How Is the North America Construction Equipment Market Shifting by Demand and Fleet Needs?
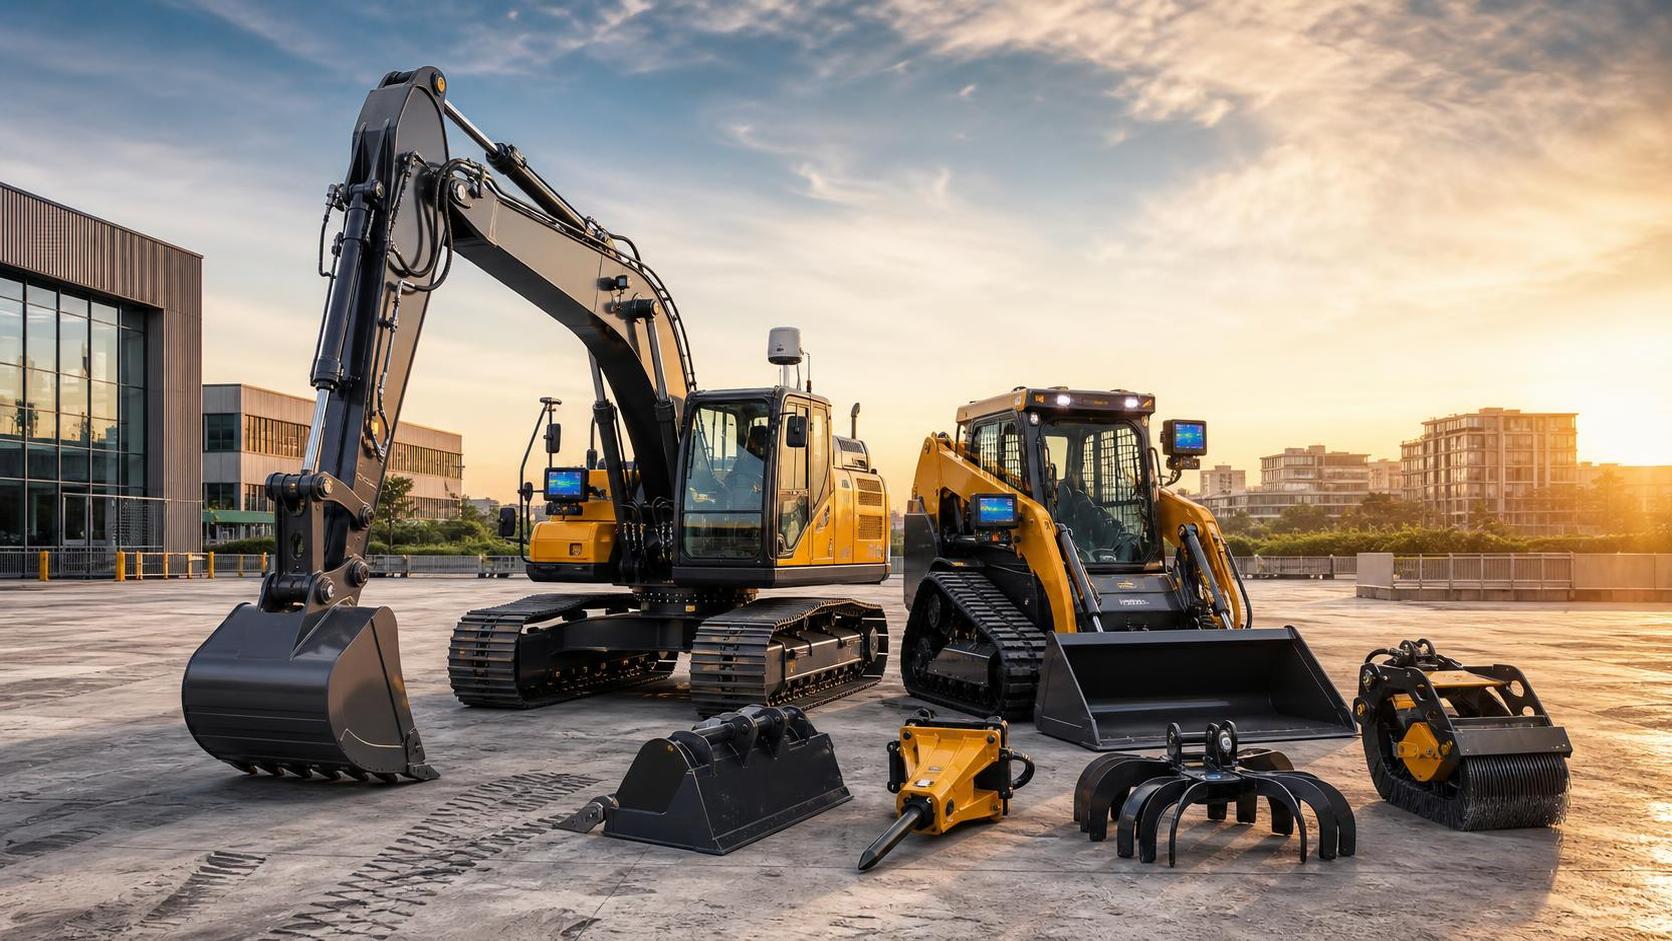
The construction equipment North America market is not simply growing or slowing; it is being rearranged. Across the U.S. and Canada, contractors are making equipment decisions with a different mindset than they did just a few years ago. Infrastructure spending still matters, housing cycles still matter, and energy projects still matter. But for dealers, distributors, and agents, the more important change is this: demand is becoming more segmented, fleet ownership is becoming more selective, and purchase timing is increasingly tied to utilization, compliance, and service confidence rather than brand habit alone.
That shift is easy to feel on the ground. A contractor that once bought a machine class on a predictable replacement schedule may now delay one purchase, rent another category, and prioritize telematics-ready units in a third. A regional fleet operator may want fewer machines overall, but better-matched machines with lower downtime risk. Municipal work, warehouse development, utility upgrades, and site preparation all pull equipment demand in different directions. The old assumption that broad market momentum will lift all machine categories equally no longer holds.
For channel players, this creates both pressure and opportunity. The winners in this market are not only moving iron; they are reading project mix, fleet age, emissions requirements, financing appetite, and rental substitution patterns with more precision.
Demand is fragmenting by application, not just by region
One of the most important developments in the North American market is that equipment demand is becoming increasingly application-specific. Broad regional labels such as “Sun Belt growth” or “Midwest infrastructure” still help frame opportunity, but they do not explain what customers are actually asking for at the branch level.
Urban redevelopment creates demand for compact and maneuverable equipment that can work in tighter footprints with lower transport complexity. Large civil packages push demand toward earthmoving, compaction, and roadbuilding support fleets. Utility and energy work often requires dependable mid-sized equipment with attachment versatility and strong uptime support. In warehousing and logistics-linked construction, buyers and renters may focus less on raw machine size and more on speed of deployment, operator familiarity, and service intervals.
For distributors, this means inventory planning can no longer rely too heavily on annualized averages. The mix matters as much as the volume. A healthy market on paper may still punish a dealer carrying the wrong machine classes, wrong attachment bundles, or wrong emissions configurations for its customer base.
Rental demand is no longer a side story
Rental has become one of the strongest forces reshaping how equipment moves through the market. That does not mean ownership is fading away. It means contractors are using ownership and rental more strategically.
Shorter project visibility, labor uncertainty, and higher capital discipline have made many buyers more cautious about adding machines that might sit idle between jobs. Equipment categories with variable utilization are especially exposed to this thinking. Contractors increasingly ask a practical question: if a machine will not stay busy across multiple contracts, why own it?
For dealers and agents, this changes the sales conversation. The objective is less about pushing every customer toward purchase and more about understanding where ownership still creates value. High-hour core machines with predictable use still support ownership logic. Specialized units, seasonal demand machines, and peak-capacity needs often shift toward rental or rent-to-purchase models.
This also raises a difficult challenge for traditional channels. If rental fleets absorb a larger share of customer demand, machine sales may remain active while end-user ownership patterns become less stable. Dealers that understand local rental penetration and align parts, service, used equipment, and remarketing strategies accordingly will be in a stronger position than those watching only new unit sell-through.
Fleet renewal is being driven by total cost, not age alone
North American contractors are still renewing fleets, but the logic behind replacement has changed. In the past, age or accumulated hours might have served as the main trigger. Today, replacement decisions are more likely to reflect a combination of maintenance cost inflation, fuel efficiency, resale value timing, operator retention, and digital fleet visibility.
Aging equipment is not automatically a problem if it remains productive, easy to service, and suitable for current job requirements. On the other hand, a relatively newer machine can become less attractive if it lacks the telematics integration, compliance profile, or hydraulic flexibility required by newer project types.
This is why the construction equipment North America market is seeing sharper attention on lifecycle economics. Contractors are comparing the hidden costs of extending fleet life against the burden of new equipment payments. They are also watching used market conditions more carefully. If resale channels are supportive, replacement decisions become easier. If used values soften or machine turnover slows, fleet renewal can stall even when operational logic supports it.
For channel partners, the lesson is clear: replacement marketing needs to be built around lifecycle math, uptime planning, and application fit. Generic “newer is better” messaging feels increasingly disconnected from how buyers actually decide.
Emissions rules and compliance expectations are influencing fleet composition
Regulation is not a background issue anymore. While North America does not move as a single regulatory block, emissions standards, low-emission jobsite expectations, and public project requirements are shaping fleet choices in visible ways.
For many buyers, the issue is less about headline policy and more about practical access. Can this machine enter the projects we want to bid? Will it align with municipal or institutional procurement requirements? Are we exposing ourselves to future retrofit costs or restrictions? Those questions matter even to customers that are not pursuing aggressive sustainability branding.
Dealers serving public works contractors, urban builders, and larger commercial accounts should expect more questions around fuel efficiency, idle reduction, and the long-term viability of specific machine platforms. In some cases, compliance concern will accelerate purchase. In others, it will delay buying while customers wait for clearer technology direction.
This is where market intelligence becomes valuable beyond simple sales support. For organizations tracking building materials, project evolution, and the broader modernization of residential and commercial space, equipment demand cannot be read in isolation. Changes in green building standards, utility retrofits, water infrastructure upgrades, and smarter site planning all influence what kinds of machines are needed and how fleets are justified.
Compact, versatile, and attachment-ready machines are gaining strategic importance
If there is one practical pattern running through much of the market, it is the rise of versatility. Contractors want machines that can cover more use cases without creating unnecessary fleet sprawl. Compact track loaders, mini excavators, backhoes in the right service geographies, and mid-sized excavators with strong attachment compatibility continue to benefit from this preference.
This does not mean large equipment categories are losing relevance. Major civil and energy projects still require substantial earthmoving capacity. But for a broad range of contractors, especially those balancing mixed project portfolios, versatility now carries real financial value. One machine that can move between grading, material handling, trenching, and site cleanup tasks may justify itself faster than a more specialized asset that performs brilliantly but sits too often.
Distributors should pay attention not only to base unit demand but to attachment ecosystems, transport convenience, and operator learning curves. In a cautious market, the easiest machine to justify is often the one that solves several problems at once.
Technology is becoming a fleet filter, not a premium add-on
Telematics, machine monitoring, and digital service visibility used to feel optional for some parts of the market. That is changing. Even customers that are not deeply digital are starting to see technology as a practical tool for maintenance planning, utilization tracking, theft deterrence, and operator accountability.
For multi-branch contractors and fleet managers, technology can influence procurement in a straightforward way: if a machine cannot be monitored easily, serviced predictably, or integrated into fleet reporting, it creates friction. In a market where labor is tight and margin discipline is sharper, friction is expensive.
This matters for agents and dealers because product knowledge must now extend beyond engine specs and breakout force. Buyers increasingly want clarity on data access, service alerts, software support, and whether digital features are useful in real fleet conditions rather than impressive in a brochure.
There is also a secondary effect. Better visibility into fleet utilization can reduce unnecessary purchases. That may sound negative for sales, but it often improves the quality of the sale. Customers that understand their fleet better tend to buy with stronger intent and clearer replacement logic.
Labor constraints are quietly influencing machine demand
North America’s labor challenge continues to shape equipment decisions in ways that are easy to underestimate. Contractors are not only short on people; they are often short on highly experienced operators, field mechanics, and project managers. That reality changes what kind of equipment is attractive.
Machines that are easier to operate, simpler to maintain, and faster to deploy gain an edge. So do platforms with familiar controls across product lines, dealer-supported training, and service accessibility. In some segments, fleet standardization becomes more important than chasing marginal spec advantages from mixed brands or scattered machine types.
This creates a subtle but meaningful opening for distributors. The right value proposition may be operational simplicity rather than maximum capability. If a customer can put a machine to work with less training risk and less service uncertainty, that may outweigh a small difference in upfront cost.
What dealers, distributors, and agents should watch next
Reading the construction equipment North America market now requires more than following macro headlines. Channel players should monitor several moving layers at once.
First, keep a close eye on project type, not just aggregate construction sentiment. Civil, utility, industrial, warehousing, residential, and municipal work do not generate the same fleet behavior.
Second, study ownership-versus-rental substitution at the category level. A branch may see healthy machine movement while long-term ownership appetite weakens in selected classes.
Third, evaluate fleet age together with service cost trends. Older fleets can create deferred replacement demand, but only if contractors believe new units will deliver meaningful lifecycle improvement.
Fourth, prepare for more selective inventory decisions. Breadth alone is not strategy. Local relevance, attachment matching, and availability timing increasingly decide whether a channel partner captures the order.
Finally, strengthen intelligence links beyond equipment itself. Construction demand is increasingly connected to how buildings, infrastructure, utilities, and interior systems evolve. That wider view matters. As sectors such as smart buildings, water-efficient systems, retrofit-heavy commercial spaces, and energy-conscious development continue to shape project pipelines, equipment demand will follow those structural changes.
The market is shifting, but not in one direction. It is becoming more conditional, more segmented, and more tied to project economics at the fleet level. For dealers, distributors, and agents, that is the central takeaway. Opportunity remains strong, but it belongs to those who can translate regional demand into machine mix, convert uncertainty into lifecycle guidance, and support customers who are no longer buying equipment simply to own it, but to fit a sharper, more accountable operating model.
Industry Briefing
Get the top 5 industry headlines delivered to your inbox every morning.