Middle East Construction Industry Outlook: Key Growth Drivers and Project Risks
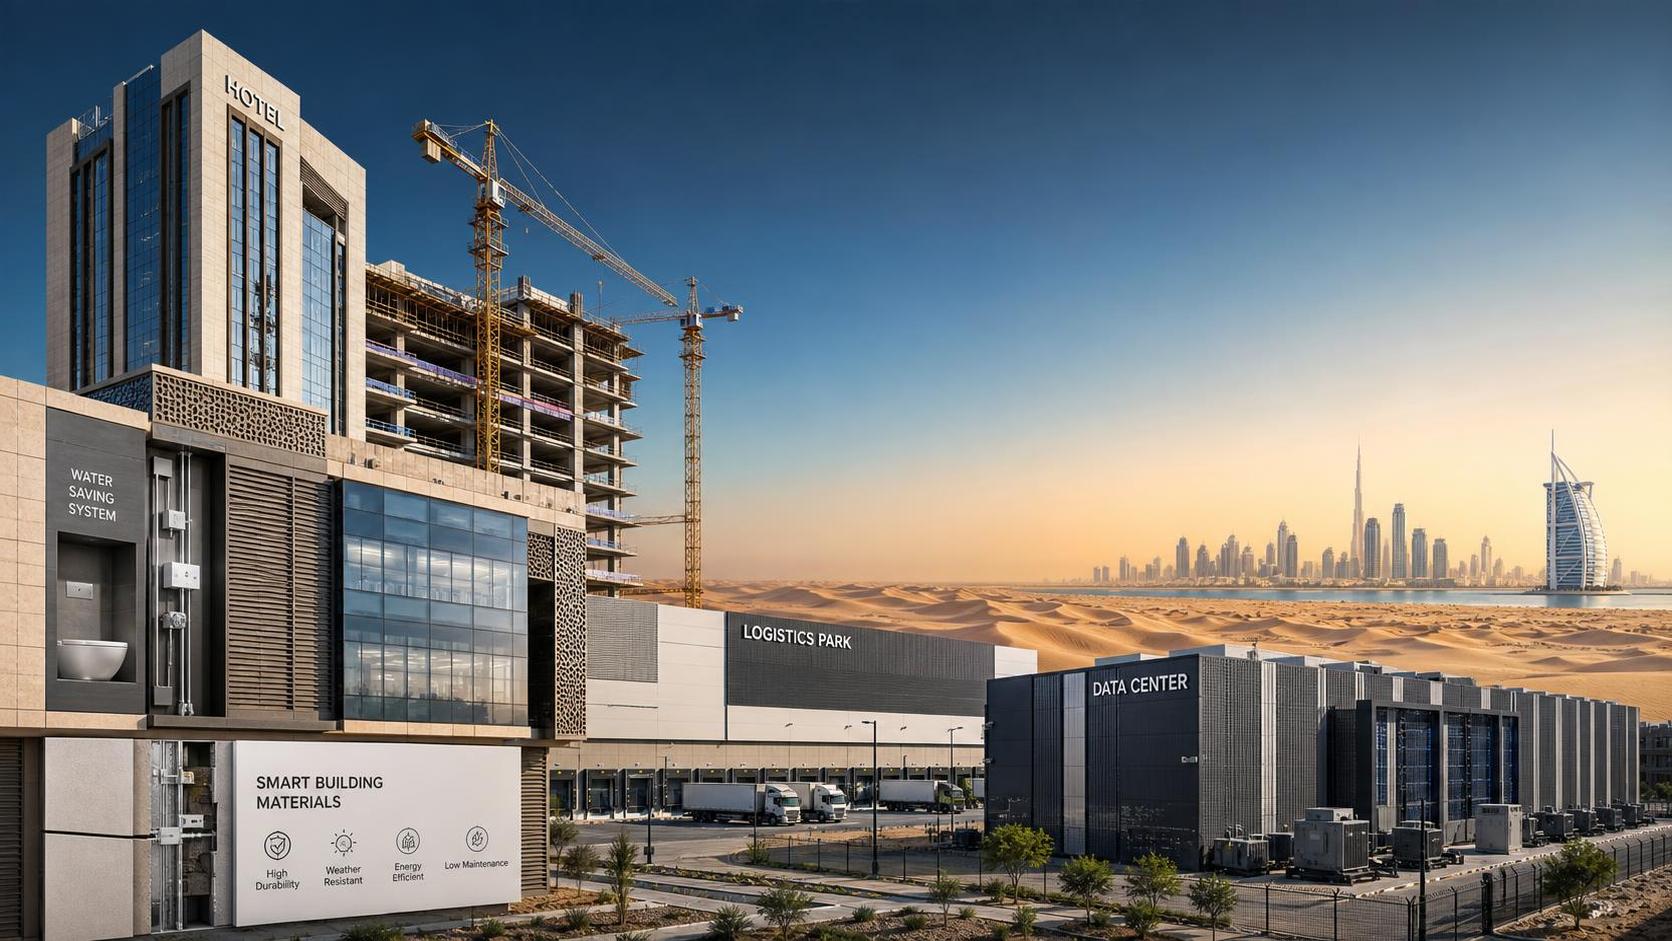
Why the Middle East construction cycle looks different this time
The construction industry Middle East is not simply growing on the back of oil wealth or headline-grabbing mega projects. That old reading is too shallow for what is happening now. Across the Gulf and parts of the wider region, construction demand is being reshaped by a more practical mix of state-led diversification, urban population pressure, tourism ambitions, logistics expansion, and a rising expectation that buildings must perform better over their full life cycle.
For decision-makers, the headline opportunity is clear: project pipelines remain active in transport, hospitality, mixed-use urban districts, data centers, industrial zones, housing, healthcare, and education. But the harder question is not whether there is work. It is where capital is most likely to convert into bankable, deliverable projects without getting trapped by procurement volatility, schedule slippage, changing specifications, or fragmented compliance requirements.
This is also why material and interior intelligence matter earlier than many project teams expect. In the region, selection decisions around sanitary systems, water-saving fittings, surface materials, kitchen and bath technologies, antimicrobial finishes, and smart access hardware often move from a design preference to a project risk issue very quickly. GIAM has positioned itself in that intersection, tracking how building materials, sanitary spaces, and smart living systems are no longer a finishing-layer topic, but part of how developers and manufacturers read demand, regulation, and long-term asset positioning.
The strongest growth drivers are no longer all the same
One mistake outsiders make is treating the Middle East as a single construction market. It is not. The Gulf states may share some demand patterns, but project logic differs from country to country. In some markets, public investment and sovereign-led urban transformation dominate. In others, trade connectivity, industrial expansion, or tourism-linked real estate are more decisive. That changes what gets built, how fast procurement moves, and which suppliers can hold margin.
Still, a few region-wide drivers are hard to ignore.
Urban diversification is one. Governments want cities that do more than house administrative functions or luxury towers. They want districts that support services, manufacturing, digital infrastructure, retail, education, culture, and liveability. That translates into demand not just for structural construction, but for durable interior systems and specification-grade products that can meet heavy traffic, water efficiency, hygiene expectations, and brand positioning at the same time.
Another driver is hospitality and destination development. Hotels, branded residences, entertainment venues, waterfront projects, and mixed-use tourism zones are multiplying in several markets. These projects tend to be design-sensitive and globally benchmarked. Developers are under pressure to deliver a visible guest experience, which means material selection becomes strategic. Premium surfaces, bathroom systems, acoustic performance, touchless controls, and smart access solutions are often evaluated not only on appearance, but on maintenance cycles, replacement cost, and operational resilience in hot, high-use environments.
Industrial and logistics construction is also pulling more weight than before. Warehousing, ports, free zones, food processing, and downstream manufacturing support a different class of demand—less about visual drama, more about speed-to-operation, utility reliability, code compliance, and total cost of ownership. In this segment, the procurement conversation usually gets technical fast: drainage systems, water control, corrosion resistance, cleaning requirements, worker amenities, and smart monitoring are often more important than imported design narratives.
Sustainability is becoming a procurement filter, not just a branding line
Sustainability in the region is sometimes discussed too abstractly. On the ground, what matters is whether performance requirements are entering tenders, design briefs, and authority approvals in a way that affects product selection and engineering scope. In many cases, they are.
Energy efficiency remains central, but water management is just as important in the Middle East construction outlook. Water-saving technologies, efficient sanitary systems, leak control, low-flow fixtures, and smarter hydraulic design are not optional talking points in a water-stressed region. They increasingly influence both new-build specifications and retrofits. The same goes for materials that support hygiene, lower maintenance burdens, or contribute to indoor environmental quality in hospitals, schools, hospitality assets, and premium residential schemes.
This is one reason intelligence platforms focused on building materials and sanitary spaces are gaining relevance. GIAM’s Strategic Intelligence Center, with its cross-disciplinary lens spanning material science, hydraulic design, and industrial economics, reflects a market reality: the competitive edge is often hidden in specification shifts, tariff changes, or the growing preference for systems that can satisfy efficiency and user-experience demands together.
There is a practical warning here. Many teams still treat sustainability compliance as something to reconcile late in the design process. In the Middle East, that can become expensive. If a project has already locked in certain façade, sanitary, or interior material assumptions and later runs into local efficiency standards, utility constraints, or owner-driven ESG targets, redesign costs can surface at exactly the wrong time.
Where project risk really shows up
The region’s biggest project risks are rarely mysterious. They are usually visible early, but underestimated because the market narrative is dominated by ambition.
The first is delivery complexity. Mega-project environments often involve layered stakeholders, evolving masterplans, phased approvals, and interface issues across contractors, consultants, operators, and authorities. That complexity is manageable when governance is tight. It becomes dangerous when packages are rushed to market before the design basis is stable. In that situation, contractors price uncertainty unevenly, suppliers struggle with repeated revisions, and procurement teams end up comparing bids that are not truly equivalent.
The second is supply-chain exposure. Even when headline logistics are improving, construction inputs can still be affected by shipping disruptions, tariff adjustments, geopolitical tensions, or local content expectations. This matters especially for imported finishes, specialized bathroom systems, smart hardware, and custom components with limited regional stock. A product can look acceptable on cost and performance, then become a schedule liability because lead times were never verified against actual project sequencing.
Then there is labor and execution quality. In fast-moving markets, shortages may not appear only as a lack of workers. They show up as uneven subcontractor capability, weak installation control, or insufficient commissioning discipline. This is particularly relevant for spaces where user experience depends on details: wet areas, hotel bathrooms, healthcare sanitation zones, and smart residential systems. A high-end specification installed badly is not a premium outcome; it is a defect claim waiting to happen.
Not every attractive project pipeline is equally investable
From a boardroom perspective, the more useful question is not “Which country has the biggest announced pipeline?” but “Which subsegments have the clearest path from announcement to delivery?” Announced value and executable demand are not the same thing.
Hospitality can be attractive when demand fundamentals, brand standards, and financing align. Yet it is also vulnerable to over-customization and late design change. Residential can look more straightforward, but product mix matters. Affordable or mid-market units have different value-engineering pressure from branded or luxury schemes, and that changes acceptable cost for smart kitchen, bath, and interior systems. Institutional projects may offer steadier demand, but often come with more rigid compliance review and documentation requirements.
For manufacturers and solution providers, this means segmentation discipline matters. It is usually a mistake to approach the Middle East as a single premium market for imported materials. Some projects reward innovation and differentiated performance. Others are far more price-sensitive and driven by local standardization, maintainability, and approved vendor lists.
What smart decision-makers are doing differently
The firms navigating this market well are usually not the loudest. They are the ones tightening their information loops before committing capital or inventory. They track regulatory movement, authority preferences, tariff changes, approved standards, and owner-side design expectations continuously rather than waiting for a tender release.
That is where market intelligence becomes operational, not decorative. A platform like GIAM is useful when it helps teams connect high-level trends with category-level implications: which building standards are shifting, where water-saving systems are gaining traction, how antibacterial material demand is being specified, or whether smart locks and connected kitchen-bath solutions are moving from luxury differentiators into baseline expectations in certain urban formats.
There is also a more grounded habit worth noting: good regional players respect localization. They do not assume a globally successful material, fixture, or smart system will sell itself. They ask whether it fits climate realities, maintenance culture, local installation capability, replacement-part availability, and the commercial logic of the asset. That sounds obvious, but a surprising number of project setbacks begin with a product that was technically impressive and commercially misread.
The near-term outlook: selective growth, sharper scrutiny
The near-term direction for the construction industry Middle East still points to active opportunity, but the market is likely to reward precision more than broad enthusiasm. Capital will continue to favor projects that align with diversification agendas, livability goals, infrastructure necessity, and credible operating models. At the same time, investors, developers, and procurement leaders are becoming less tolerant of vague assumptions around cost, delivery, and performance.
That makes this a strong market for companies that can do three things well: read demand at segment level, translate sustainability and smart-living trends into practical specifications, and manage risk across sourcing, compliance, and execution. It is a tougher market for those relying on generic regional narratives or assuming every large announcement will become near-term revenue.
If there is one useful takeaway, it is this: in the Middle East, project ambition still matters, but project discipline matters more. The winners will not necessarily be those with the widest exposure. They will be the ones making better calls, earlier—before design drift, procurement gaps, or misplaced product assumptions become expensive facts.
Industry Briefing
Get the top 5 industry headlines delivered to your inbox every morning.