Material Science Trends Report: Emerging Materials Reshaping Building Products
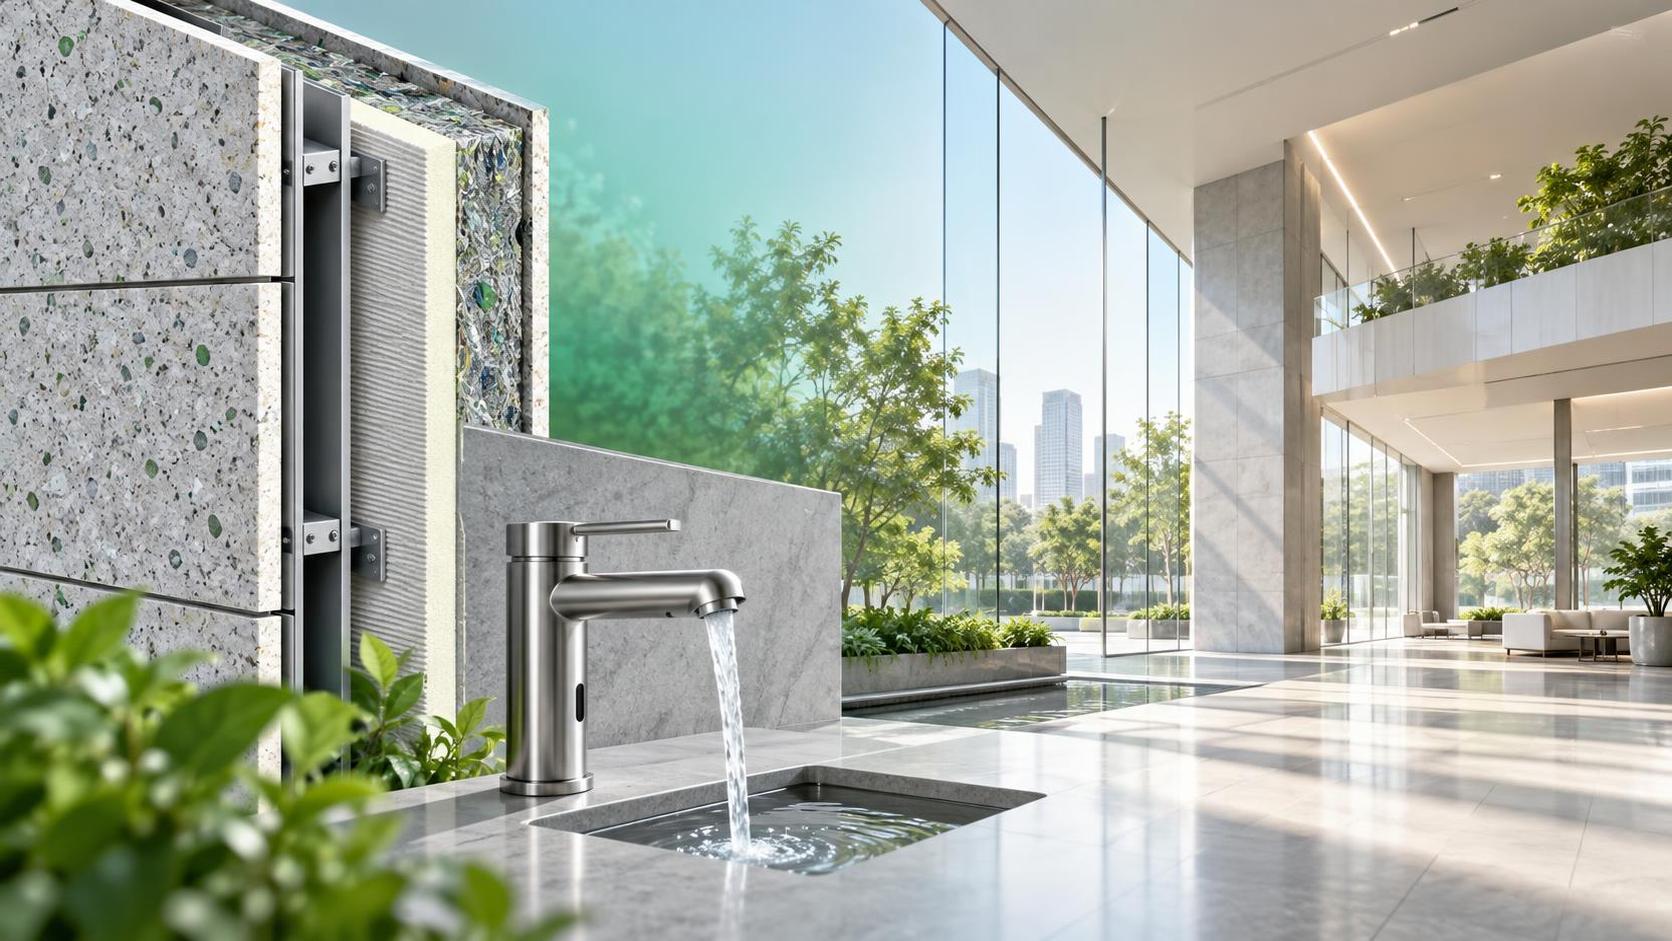
Material Science Trends Report: Emerging Materials Reshaping Building Products
This Material Science Trends Report examines the emerging materials redefining building products, from low-carbon composites and antibacterial surfaces to high-performance insulation and intelligent water systems.
For business decision-makers, these innovations are no longer technical upgrades. They are strategic levers for meeting stricter regulations, strengthening project competitiveness, and capturing demand in sustainable, connected spaces.
What Decision-Makers Are Really Searching For
Executives researching material science trends usually want more than a list of promising innovations. They need to understand which materials can create commercial advantage within practical investment horizons.
The central question is not whether advanced materials will influence construction. They already are. The question is where adoption will generate measurable value for manufacturers, developers, distributors, and specification teams.
That value may appear through lower embodied carbon, reduced operating costs, easier compliance, stronger health credentials, longer product life, or improved differentiation in competitive project tenders.
For building-product businesses, the most valuable materials are rarely those with the most impressive laboratory performance. They are materials that solve a visible market problem at scale.
A high-performing material must also fit existing manufacturing processes, supply chains, certification pathways, installation methods, and buyer expectations. Commercial readiness matters as much as scientific novelty.
This Material Science Trends Report therefore focuses on decision criteria: regulatory exposure, customer demand, cost implications, product compatibility, operational risk, and the likelihood of premium-market acceptance.
Leaders should treat material selection as portfolio strategy. The aim is to identify where a material can protect current revenue, unlock higher-margin applications, or prevent future compliance-related disruption.
Low-Carbon Materials Are Becoming a Market Access Requirement
Low-carbon materials have moved from a sustainability preference to a commercial requirement in many public, institutional, hospitality, and premium residential construction projects.
Developers increasingly evaluate products through environmental product declarations, lifecycle assessment data, recycled content, local sourcing, and alignment with green-building certification frameworks.
This shift is especially significant for carbon-intensive categories such as cementitious products, ceramics, metals, insulation, engineered stone, sanitaryware, and large-format architectural panels.
Manufacturers are responding with recycled aggregates, supplementary cementitious materials, bio-based binders, lower-temperature firing processes, recycled aluminum, and lightweight composite alternatives.
However, low-carbon positioning only creates value when environmental claims can be substantiated. Unsupported marketing language exposes companies to procurement rejection, reputational damage, and greenwashing scrutiny.
Decision-makers should prioritize materials supported by verified lifecycle data, credible third-party certification, and a transparent explanation of carbon boundaries and calculation assumptions.
Carbon reduction should also be assessed alongside durability. A product with lower initial emissions may create weaker lifecycle economics if it requires earlier replacement, more maintenance, or complex end-of-life handling.
For many companies, the strongest near-term opportunity is not a complete material replacement. It is redesigning established product lines with lower-carbon inputs while retaining familiar performance and installation characteristics.
This approach limits adoption friction. Buyers can specify a more sustainable option without changing installation teams, tooling requirements, maintenance protocols, or the wider project design.
In procurement-heavy sectors, credible low-carbon products can improve tender eligibility. In premium markets, they can also support higher-value positioning when performance and visual quality remain uncompromised.
High-Performance Insulation Is Shifting From Energy Savings to Building Resilience
Insulation remains one of the most commercially important categories in the material science trends report because energy efficiency regulations continue to tighten across global construction markets.
Yet the market is evolving beyond basic thermal resistance. Buyers increasingly want materials that address fire safety, moisture control, acoustics, indoor air quality, and space constraints simultaneously.
Vacuum insulation panels, aerogel-enhanced products, advanced mineral wool, rigid foam alternatives, and bio-based insulation systems are expanding design choices for difficult building envelopes.
High-performance insulation is especially valuable in renovation projects. Existing buildings often have limited cavity depth, making conventional insulation unsuitable for ambitious energy-upgrade targets.
For developers, thin insulation systems can preserve rentable floor area. For architects, they can enable demanding facade details without sacrificing energy performance or visual intent.
However, thermal claims alone do not determine investment value. Decision-makers must examine installation sensitivity, moisture behavior, fire classification, compressive strength, repairability, and long-term degradation risk.
A material that performs well under laboratory conditions can disappoint in real buildings if detailing, transport, cutting, fastening, or site workmanship compromise its designed performance.
Procurement teams should therefore request performance data that reflects intended use conditions. Relevant evidence includes aging tests, fire testing, thermal bridge analysis, and documented installation guidance.
The strongest market opportunities are likely to emerge where high-performance insulation supports compliance with energy codes while reducing disruption in renovation, modular construction, or constrained urban developments.
Antibacterial and Hygienic Surfaces Need Evidence, Not Just Claims
Antibacterial surfaces have become a prominent area of material innovation, particularly in healthcare, education, hospitality, public facilities, kitchens, bathrooms, and high-density residential developments.
These products may incorporate silver ions, copper compounds, photocatalytic coatings, antimicrobial polymers, nonporous glazes, or surface structures designed to reduce contamination retention.
The commercial appeal is clear. Hygienic surfaces support wellness-oriented design, simplify cleaning narratives, and give manufacturers a way to differentiate products in visually mature categories.
But this category also carries significant risk. Antibacterial claims can be misunderstood by customers, regulators, and building occupants if product limitations are not communicated precisely.
An antimicrobial surface does not eliminate cleaning requirements. It may reduce microbial growth under specific test conditions, but it cannot replace cleaning protocols, ventilation, or infection-control procedures.
Business leaders should require clear test methods, named standards, verified organisms, defined contact times, and realistic statements about how performance changes with wear and cleaning chemicals.
Material selection must also consider durability. Coatings can lose effectiveness through abrasion, aggressive cleaning, ultraviolet exposure, or repeated contact with oils and detergents.
For sanitaryware, tiles, faucets, countertops, and door hardware, surface performance should be assessed alongside stain resistance, chemical resistance, tactile quality, color stability, and repairability.
The most defensible positioning combines hygiene with broader value. A surface that is easy to clean, durable, low-porosity, and visually stable offers stronger commercial utility than an isolated antimicrobial claim.
Companies should also consider regional rules. Health-related marketing language is regulated differently across markets, and product communications must align with local legal and certification requirements.
Water-Saving Materials and Systems Are Creating New Specification Value
Water efficiency is becoming a defining consideration in sanitary spaces, commercial interiors, hospitality projects, and multifamily developments, particularly in regions facing water stress or rising utility costs.
Material science supports this transition through advanced valve components, durable seals, corrosion-resistant alloys, hydrophobic coatings, sensor-compatible finishes, and improved internal flow-path engineering.
In kitchen and bath products, water savings cannot come at the expense of user experience. Weak flow, inconsistent temperature control, noise, leakage, and difficult maintenance quickly undermine adoption.
Successful water-saving products balance hydraulic efficiency with comfort, reliability, hygiene, and serviceability. This is especially important for hotels, airports, hospitals, offices, and public restrooms.
Decision-makers should evaluate total water performance rather than fixture flow rates alone. Usage patterns, sensor calibration, pressure variation, maintenance intervals, and leak detection all influence actual savings.
Smart water systems add another layer of value. Sensors and connected controls can identify abnormal consumption, detect leaks early, manage temperature settings, and support portfolio-wide facility reporting.
For property owners, these systems can reduce operational costs and water-loss exposure. For manufacturers, they create opportunities for recurring service, data-enabled maintenance, and premium specification packages.
Yet connected water products require careful governance. Cybersecurity, software support commitments, interoperability, data ownership, and replacement-part availability should be assessed before large-scale deployment.
Materials remain central because smart systems depend on reliable physical components. A sophisticated sensor cannot compensate for poor valve durability, corrosion, seal failure, or inconsistent manufacturing quality.
Composites and Advanced Surfaces Are Redefining Design Freedom
Composite materials are expanding quickly across facades, wall systems, countertops, doors, flooring, furniture, partitions, and bathroom applications because they combine performance with design flexibility.
Engineered surfaces can offer reduced weight, dimensional stability, moisture resistance, large-format continuity, and visual effects that would be difficult or expensive to achieve with natural materials.
For commercial projects, lightweight composites may reduce structural loading and simplify handling. For manufacturers, they can enable repeatable finishes, efficient fabrication, and broader customization options.
The commercial risk lies in assuming that visual appeal alone will sustain demand. Buyers increasingly ask about scratch resistance, UV stability, repairability, flame performance, emissions, and end-of-life options.
Some composites remain difficult to recycle because their components cannot be separated economically. This can become a strategic weakness as circularity requirements become more explicit in procurement criteria.
Businesses should distinguish between recyclable in theory and recoverable in practice. A credible circularity strategy includes collection channels, take-back programs, recycled-content availability, and reuse economics.
Material transparency is equally important for interior products. Architects and corporate clients may require information on volatile organic compounds, formaldehyde, plasticizers, and other indoor environmental factors.
Composites with strong documentation can command a premium in healthcare, education, workplace, hospitality, and high-end residential markets where specifications increasingly include wellness and sustainability criteria.
Intelligent Materials Will Matter Most Where They Reduce Operational Complexity
Intelligent materials include products that respond to temperature, moisture, light, electrical signals, pressure, or usage conditions. Their relevance is growing across connected buildings and adaptive interiors.
Examples include electrochromic glazing, phase-change materials, self-healing coatings, moisture-responsive membranes, conductive surfaces, smart glass, and sensor-integrated plumbing or access-control components.
These technologies attract attention because they promise responsive environments. However, business value depends on whether they reduce operating complexity or create a more difficult maintenance burden.
Electrochromic glass, for example, may reduce glare and cooling loads while improving occupant comfort. Its value is strongest in buildings with high solar exposure and sophisticated energy-management objectives.
Phase-change materials can help moderate indoor temperature swings. Their commercial potential is greater where energy peaks, comfort requirements, and building-envelope limitations make conventional solutions less effective.
Sensor-integrated building products can provide useful operational data, but only when the data reaches the people who can act on it. Unused dashboards do not create returns.
For executives, the key question is integration. Can the product communicate with existing building-management systems, maintenance platforms, and security infrastructure without expensive custom development?
Companies should also evaluate lifecycle support. Intelligent products may involve firmware updates, replacement electronics, calibration, cybersecurity patches, and vendor continuity risks beyond standard material warranties.
The best investments are often focused rather than universal. A smart material should solve a defined operational problem in a high-value location, not merely demonstrate technological ambition.
How to Build a Practical Material Investment Portfolio
A strong material innovation strategy begins by separating immediate commercial opportunities from longer-term research initiatives. Both matter, but they require different governance, budgets, and success measures.
Near-term opportunities usually involve material substitutions, formulation improvements, improved coatings, recycled-content upgrades, or components that fit current production and distribution systems.
Longer-term initiatives may include novel bio-based materials, advanced nanomaterials, fully circular composites, autonomous repair systems, or deeply integrated smart-building products.
Decision-makers should map every candidate material against five questions: What market problem does it solve, what regulation affects it, what proof is required, and what margin potential exists?
The fifth question is operational: can the company source, manufacture, certify, install, service, and scale the material without creating unacceptable supply-chain or quality risks?
It is useful to establish a cross-functional review team. Product engineering, procurement, operations, sales, compliance, sustainability, and technical service often identify different risks and opportunities.
Sales teams can reveal whether customers will pay. Operations can identify tooling constraints. Compliance specialists can assess claims and certification. Procurement can expose supply concentration or volatility.
Pilot programs should be designed around commercial learning, not only technical validation. Track installation time, rejection rates, service calls, customer feedback, certification outcomes, and willingness to pay.
Companies should also avoid treating sustainability and performance as separate projects. The strongest building products increasingly deliver both: lower environmental impact and better functional outcomes.
A portfolio approach helps prevent overinvestment in a single trend. It also ensures that the business retains options as regulations, raw-material costs, and customer specifications continue to change.
Where the Material Science Trends Report Points Next
The next phase of building-product innovation will be defined by convergence. Materials will increasingly combine carbon performance, health value, durability, digital connectivity, and architectural expression.
This creates an opportunity for companies that can translate technical capability into clear specification value. Buyers do not purchase material science; they purchase lower risk and better project outcomes.
Manufacturers that provide reliable data, credible certifications, installer support, and clear lifecycle arguments will be better positioned than competitors relying only on product novelty.
For distributors and project-specification teams, the opportunity is to become trusted interpreters. Customers need help comparing claims, understanding tradeoffs, and selecting solutions appropriate to actual building conditions.
The most successful market participants will not chase every innovation. They will identify the material trends that align with their category, customer base, manufacturing strengths, and regional regulatory exposure.
Conclusion
This Material Science Trends Report shows that emerging building materials are becoming decisive commercial tools, not peripheral research topics. Low-carbon, hygienic, efficient, adaptive, and intelligent products are reshaping specification decisions.
For enterprise leaders, the practical priority is disciplined selection. Invest where material innovation improves compliance, project value, operating performance, customer trust, and defensible margin potential.
The winning strategy is evidence-led and application-specific. Companies that connect advanced materials with verified performance and practical delivery will help define the next generation of sustainable, intelligent spaces.
Industry Briefing
Get the top 5 industry headlines delivered to your inbox every morning.