Construction industry insights behind slower material turnover
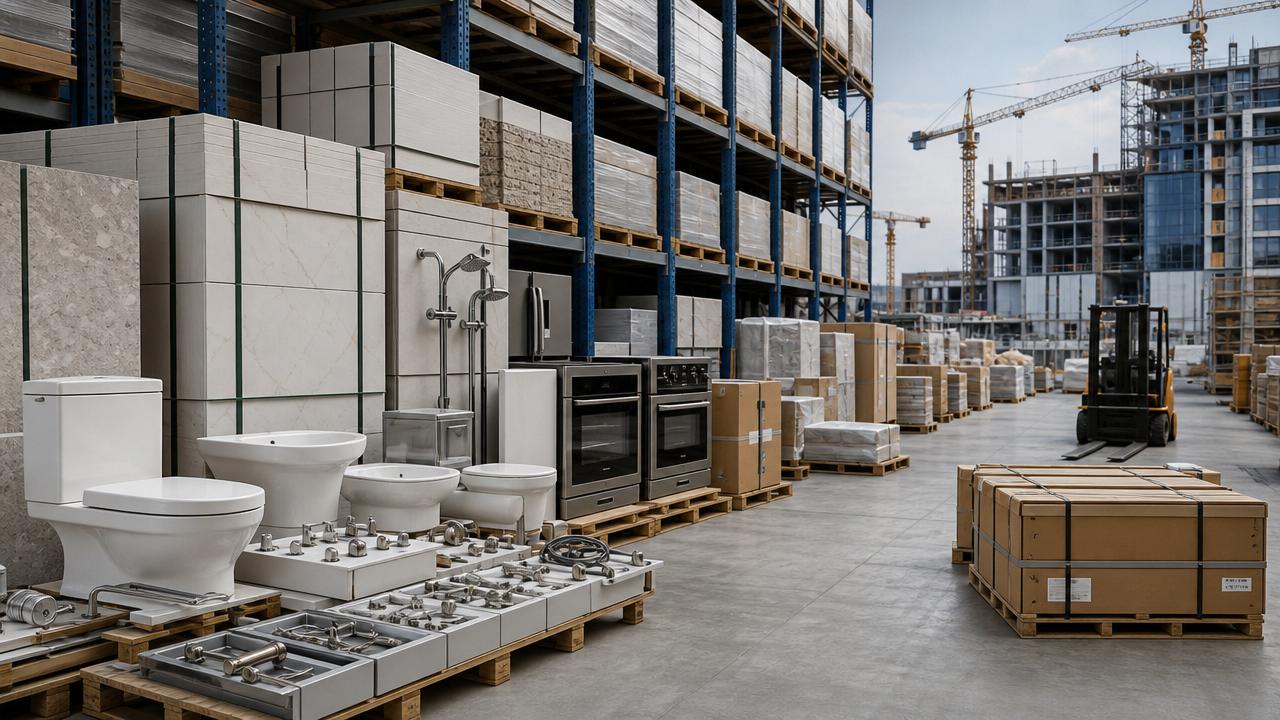
Construction industry insights: why slower material turnover matters now
Slower material turnover is not only a logistics problem. It often reveals hidden pressure across pricing, project timing, cash flow, and downstream confidence.
These construction industry insights show how inventory signals can explain broader shifts in the global building materials market.
When tiles, sanitary products, hardware, boards, or smart kitchen systems move more slowly, the cause is rarely single-layered.
Demand may be softening in one segment, while project approvals delay in another. At the same time, premium categories may remain stable.
For GIAM, reading these signals is essential. Better intelligence links hard construction data with spatial design trends and real commercial movement.
When residential projects slow, turnover pressure appears first in finish materials
Residential construction often shows turnover stress earlier than other segments. Finishing materials usually feel the slowdown before structural products.
That happens because completion timelines shift quickly when household confidence weakens, financing tightens, or developers stage deliveries more cautiously.
Useful construction industry insights come from watching categories tied to move-in readiness rather than ground-breaking activity alone.
Typical warning signs in this scenario
- Ceramic tiles stay longer in channel warehouses.
- Bathroom fixtures shift from premium to mid-range demand.
- Smart kitchen packages face delayed installation orders.
- Color and style variety increases, but actual replenishment slows.
In this scene, slower turnover does not always mean collapsing end demand. It may mean buyers are narrowing specifications and reducing decorative upgrades.
Products with broad compatibility usually outperform specialized finishes. Standardized dimensions and practical functions gain an advantage over trend-led stock.
In commercial fit-out cycles, delayed approvals can distort inventory signals
Commercial projects create a different pattern. Offices, retail, hospitality, and mixed-use spaces often pause at approval or redesign stages.
This means materials may stop moving even when long-term demand remains alive. The slowdown comes from decision timing, not total project cancellation.
Strong construction industry insights separate temporary pipeline friction from structural weakness in commercial interior demand.
Core judgment points
- Specification changes increase after sustainability reviews.
- Fire, hygiene, and water-saving standards reshape product selection.
- Imported premium materials face longer decision cycles.
- Contract packaging favors fewer vendors and integrated systems.
In hospitality and healthcare-adjacent spaces, anti-bacterial surfaces and efficient water systems may still rotate faster than decorative wall products.
This is why category-level reading matters. Looking only at total stock can create the wrong commercial conclusion.
Infrastructure-linked and public projects show slower turnover for different reasons
Public and institutional projects often behave differently from private construction. Funding rhythm, compliance checks, and tender sequencing shape material movement.
A slowdown here may reflect budget release timing rather than weak physical demand. Yet the inventory burden still sits in the channel.
These construction industry insights are important for categories connected to sanitation upgrades, educational buildings, transit hubs, and public housing.
What usually changes in this scenario
Standard products with certification strength hold their place. However, procurement windows become shorter and order batching becomes more aggressive.
That creates a misleading calm. Stock may look stagnant for weeks, then move suddenly when approvals unlock.
Planning for this pattern requires demand sensing, not simple average-based forecasting.
Different demand scenarios reveal different turnover risks
Material turnover slows for many reasons. The right response depends on project type, category mix, policy environment, and buyer behavior.
This table shows why construction industry insights must be scenario-based. The same slow turnover number can carry very different meanings.
How to adapt inventory strategy to each market scene
Action should follow the turnover pattern, not general market sentiment. Smarter planning protects cash flow and preserves margin quality.
Recommended adjustments
- Segment inventory by application scene, not only by product family.
- Separate regulatory-driven demand from style-driven demand.
- Track completion-stage indicators for interior-facing materials.
- Review premium stock exposure where redesign risk is high.
- Bundle compatible products to support integrated project decisions.
- Use regional policy and tariff signals to adjust reorder timing.
GIAM’s intelligence approach is valuable here because it connects material science, hydraulic design, and industrial economics into one operating view.
That broader lens helps identify whether weaker movement comes from channel friction, spatial trend shifts, or changing compliance requirements.
Common misreadings behind slower turnover in building materials
One common mistake is assuming all categories are slowing equally. In reality, water-saving systems, smart locks, and hygienic surfaces may outperform decorative extras.
Another mistake is reading sales value without reading sales speed. Revenue can look stable while inventory age quietly worsens.
A third mistake is ignoring specification migration. Buyers may still purchase, but they switch from custom ranges to practical standardized options.
Solid construction industry insights also warn against treating policy changes as background noise. Carbon reduction rules and water-efficiency standards directly affect product rotation.
Finally, many overlook how trade tariffs influence substitution. A slower imported line may not show falling demand, only changing sourcing logic.
What these construction industry insights suggest for the next move
The best next step is to map turnover by scene, category, and project stage. That creates a more realistic picture than broad market averages.
Focus first on where stock age is rising fastest, where premium substitutions are increasing, and where compliance-led products remain resilient.
These construction industry insights are most useful when turned into monthly review rules, reorder thresholds, and category-specific action plans.
GIAM supports this shift through high-authority intelligence on sector news, future material trends, and commercial demand signals across global building spaces.
In a slower market, better judgment beats bigger stock. The goal is not only movement, but smarter movement aligned with future spatial demand.
Industry Briefing
Get the top 5 industry headlines delivered to your inbox every morning.