Sector News Construction: How Policy, Labor, and Material Costs Are Reshaping Projects
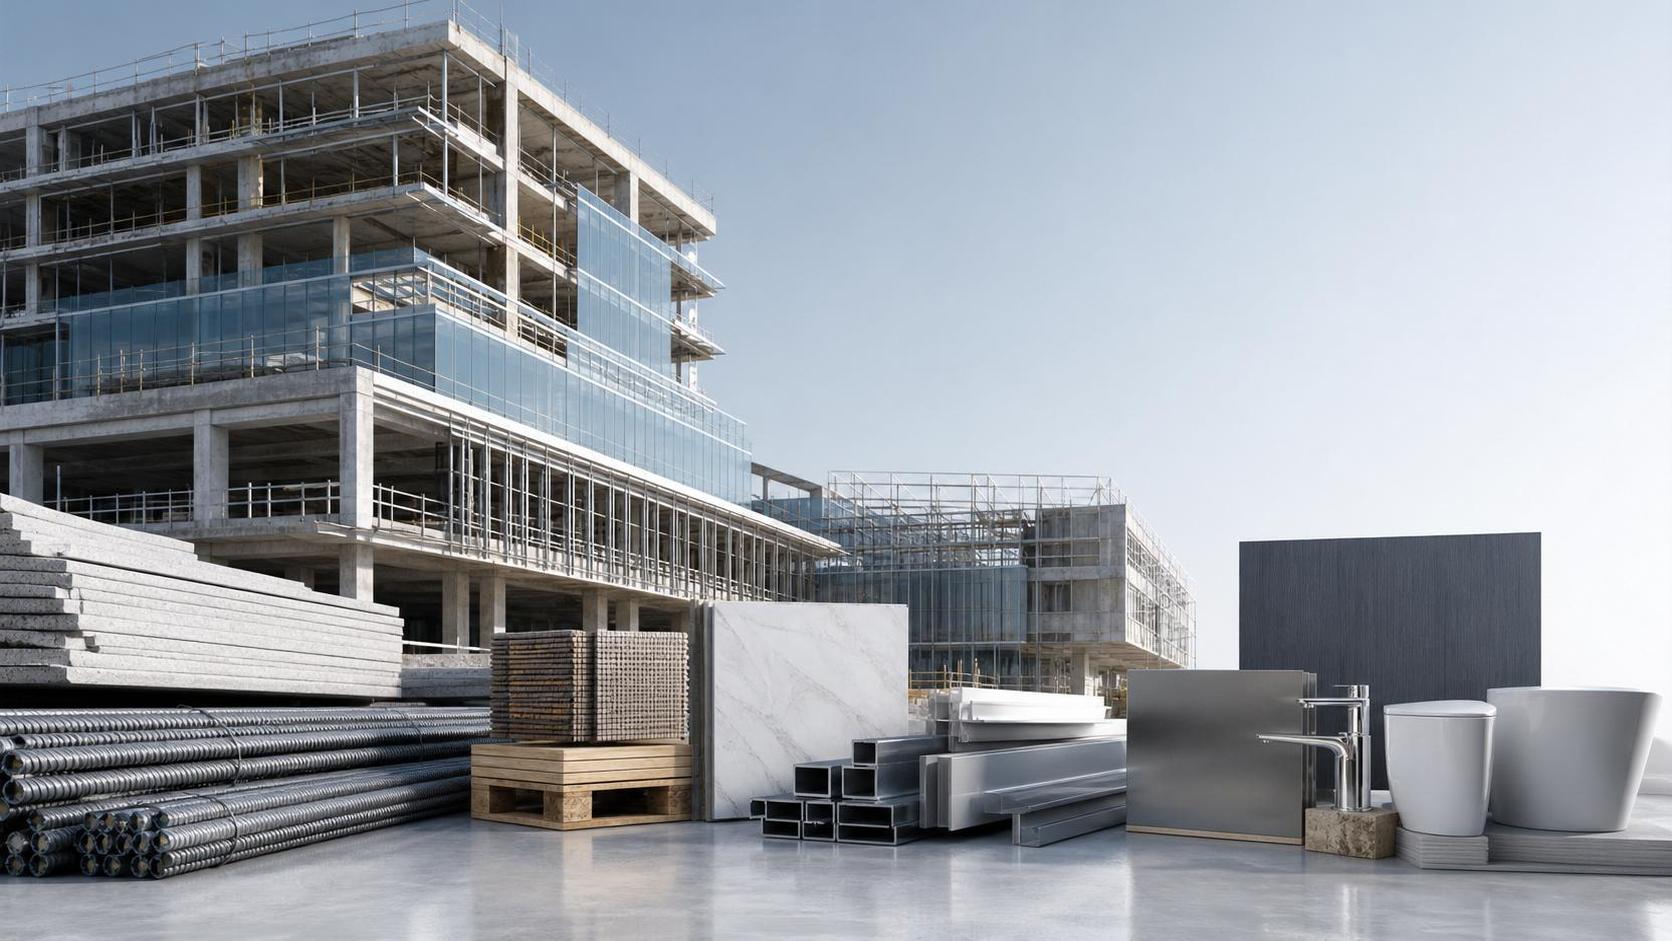
Sector news construction is moving from isolated pressure to system-wide change
Across recent sector news construction coverage, one pattern is becoming difficult to ignore. Project performance is now shaped by three connected variables at once: regulation, labor availability, and material pricing.
That shift matters because construction risk no longer sits neatly inside one contract package. A policy update can alter specifications, a labor gap can delay sequencing, and a cost spike can force redesign.
In practice, this means schedule control is increasingly tied to intelligence quality. The teams that read market signals early are better positioned to protect margins and avoid reactive decisions.
This is also why sector news construction has become more valuable than routine headline monitoring. It now serves as an early warning layer for planning, procurement, and compliance.
Within GIAM, this broader view is especially relevant. Its focus on core materials, sanitary spaces, and smart kitchen and bath systems reflects where technical standards, interior value, and project economics increasingly intersect.
Why the pressure is becoming more visible now
The latest sector news construction signals are not driven by a single cycle. They come from overlapping transitions in policy ambition, supply chain geography, and workforce demographics.
Energy codes are tightening in many markets. Water efficiency rules are expanding. Carbon reporting expectations are moving closer to actual procurement decisions rather than staying in policy documents.
At the same time, labor supply remains uneven. Skilled installers, MEP specialists, and finishing trades are harder to secure at the exact phase a project needs them.
Material costs add another layer. Prices may not always spike dramatically, yet volatility itself creates planning difficulty. Frequent revisions in freight, tariffs, and regional sourcing rules keep budgets unstable.
More importantly, these factors reinforce each other. A code-driven specification change often requires a different supplier base, which can then expose labor and lead-time gaps.
The strongest drivers behind the current reset
- Stricter building performance rules are pushing demand toward higher-grade materials and certified systems.
- Trade policy shifts are changing landed costs for tiles, fixtures, panels, metals, and smart hardware.
- A thinner skilled workforce is extending installation windows and raising supervision demands.
- Clients are asking for healthier, smarter, and lower-carbon spaces without accepting major delivery delays.
That combination explains why sector news construction now needs to be read as a strategic signal, not just as market commentary.
The biggest impact is showing up before construction even starts
One of the clearest changes is happening in preconstruction. Cost planning, material selection, and compliance review are becoming more interdependent than they were a few years ago.
When a project relies on older assumptions, early budgets can become misleading. A compliant option may now require imported components, licensed installers, or longer approval cycles.
This is especially visible in interior packages with technical performance requirements. Sanitary systems, water-saving fixtures, anti-bacterial surfaces, and connected access devices are no longer simple finish decisions.
They now sit at the meeting point of regulation, user expectations, and operating efficiency. That is where GIAM’s intelligence model becomes useful, because it tracks both materials and the evolving logic behind their adoption.
Material inflation is no longer only about price
A common reading of sector news construction still focuses on cost escalation alone. That view is now too narrow.
The more consequential issue is cost-quality-certainty balance. A lower quote may come with weaker documentation, uncertain logistics, or installation complexity that shifts expense downstream.
This matters for premium surfaces, sanitary assemblies, smart locks, and integrated kitchen systems. Products with strong end-user appeal can still create delivery risk if regional certifications or maintenance support are incomplete.
From recent sector news construction patterns, the stronger operators are not simply buying less. They are standardizing critical categories, validating alternates earlier, and tracking total installed cost with more discipline.
That approach also aligns with GIAM’s emphasis on value-chain intelligence. Material choice now affects carbon targets, service life, user health, and brand positioning inside residential and commercial spaces.
Signals worth monitoring in material decisions
- Tariff exposure on imported finish materials and hardware.
- Regional approval requirements for water-saving and smart systems.
- Availability of certified installers for specialized interior packages.
- Lifecycle performance versus headline purchase price.
Labor shortages are changing delivery logic on site
Labor pressure is often discussed as a staffing issue. On live projects, it behaves more like a sequencing issue.
When key trades are unavailable during narrow handoff windows, rework risk rises. Temporary workarounds can protect progress for a week, then create quality or coordination failures later.
Interior and architectural packages feel this acutely. Wet-area systems, prefabricated bathroom modules, high-performance panels, and smart access components all rely on precise installation order.
That is why sector news construction should be read alongside workforce capability trends. A market can show healthy demand while still underperforming because execution capacity is thinner than forecast.
More visible now is the premium placed on methods that reduce field uncertainty. Modular coordination, repeatable details, and supplier-backed installation guidance are becoming practical risk controls.
Where demand is shifting inside residential and commercial spaces
Not every category is affected in the same way. Some segments are absorbing pressure by moving toward higher-performance products rather than delaying upgrades.
In residential environments, healthier surfaces, water-saving fixtures, and connected security features continue to gain traction. Buyers are looking beyond appearance toward efficiency, hygiene, and long-term operating value.
Commercial spaces show a similar pattern, though with stronger compliance pressure. Hospitality, mixed-use, healthcare-adjacent, and premium workplace interiors increasingly require products that can satisfy both design expectations and technical standards.
This is where sector news construction links directly with GIAM’s coverage areas. Anti-bacterial materials, hydraulic design, smart kitchen systems, and intelligent access are no longer fringe topics. They are entering mainstream specification conversations.
The result is a market that rewards better information. Demand is still active, but it is becoming more selective and more evidence-based.
What deserves closer attention over the next planning cycle
The next phase of sector news construction will likely be defined by tighter integration between compliance, procurement, and product performance data.
That does not mean every project needs a major strategic overhaul. It does mean assumptions should be tested earlier and updated more often.
A practical response starts with a narrower set of checkpoints:
- Review which material categories carry the highest policy or tariff sensitivity.
- Map critical trades against actual installation sequence, not generic workforce assumptions.
- Reassess whether selected smart or sustainable products have local support capacity.
- Use market intelligence sources that connect standards, cost movement, and application trends.
This is also where GIAM’s Strategic Intelligence Center fits naturally into the conversation. Its value is less about headline aggregation and more about connecting policy shifts, commercial demand, and material evolution inside real project contexts.
The broader judgment is straightforward. Sector news construction is no longer background reading. It is part of how resilient projects are defined, priced, and delivered.
The most useful next step is to build a short review cycle around policy updates, labor exposure, and material volatility. That discipline will reveal which assumptions still hold and which ones need action before the next project phase begins.
Industry Briefing
Get the top 5 industry headlines delivered to your inbox every morning.